Micron Technology Conference Call Transcript: Memory Has Become a Strategic Asset in the AI Era, Uncertainty Remains on When Supply Will Catch Up with Demand
During the Micron earnings call, Chairman and CEO Sanjay Mehrotra stated that the data center business revenue exceeded $25 billion in the third quarter of this fiscal year, with an annualized revenue of over $100 billion, showcasing Micron's position as a leader in the AI era. AI has made memory a strategic asset in this era.
Micron has just handed in a remarkable report card that caught the market's attention. Financial data shows that the company's total revenue for the third quarter reached a record $41.5 billion, a 74% increase quarter-over-quarter and a staggering 346% year-over-year growth; the consolidated gross margin soared to 84.9%. This performance not only set a revenue record for the fifth consecutive quarter but also signaled that the storage industry is entering an unprecedented boom cycle.
Micron expects fourth-quarter revenue to reach a record $50 billion (plus or minus $10 billion), with a gross margin of around 86%. However, what is drawing more attention from Wall Street than the impressive financial report is the "fundamental reshaping" of Micron's business model currently underway.
"Foundational Business Model Has Been Disrupted": Signing a Trillion-Dollar Backlog, Garnering $18 Billion in Cash Deposits
Facing this unprecedented AI wave, Micron is reshaping profit certainty by changing the rules of the game. Currently, Micron has entered into 16 strategic customer agreements (SCAs) with customers in the data center, consumer, and automotive markets, including four large customers and three mid-sized customers.
Micron Chairman and CEO Sanjay Mehrotra stated during the meeting:
"The diffusion of artificial intelligence has structurally changed the storage industry. We are pleased to announce that we have now signed 16 strategic customer agreements (SCAs), which we expect will fundamentally change our business model."
These backlogs are far from simple memorandums of understanding; they are binding "Take-or-pay" contracts. The agreements typically span five years (from 2026 to the end of 2030), stipulating specific purchase quantities and setting price floors and ceilings.
These 16 backlogs have brought highly impactful financial moat data to the market:
1. Trillion-Dollar Backlog Revenue: Calculated based on the agreed minimum price and minimum shipment volume in the contract, the future Remaining Performance Obligation (RPO) corresponds to a backlog revenue of $1 trillion.
2. Mega Cash Flow Prepayment: In order to secure a stable capacity supply, the customer has put forth a substantial amount of money. CFO Mark Murphy revealed: "Under the SCAs signed to date, we expect to receive $22 billion in cash deposits and related financial commitments. The vast majority of this (around $18 billion) will be in the form of cash deposits."
3. Flattening Cycle Volatility: Currently, these long-term contracts have locked in Micron's approximately 20% of DRAM capacity and 33% of NAND capacity during this period. Mehrotra emphasized: "For SCAs that span price ranges, even at the bottom end of the pricing spectrum, Micron's gross margins will be very healthy, surpassing any prior peak quarter profitability levels."
"Supply Shortage to Persist Beyond 2027" "Unclear When Supply Will Catch Up with Demand"
The market is keenly focused on the sustainability of this storage boom. In response, Micron's management has provided a clear timeline assessment: the shortage is not just a current state but will also be the norm for the next two to three years. Mehrotra stated that this reliance has led to a fundamental shift in the role of memory:
"The performance of AI systems is architecturally dependent on the performance and capacity of the memory subsystem. It has elevated the role of memory in the AI world, making it a strategic asset."
Regarding the supply-demand imbalance, Mehrotra made a clear statement:
"We anticipate that due to AI-driven demand across all subsegments, coupled with structural supply constraints, the crunch will persist beyond 2027... Even though we expect industry supply to gradually improve in 2028, we still cannot see when memory supply will catch up with the ever-growing demand."
Why is supply struggling to keep pace? Micron highlighted four major structural pain points:
First, the vast and time-consuming nature of new fab projects, coupled with labor and energy infrastructure shortages; second, as nodes advance (such as the One Gamma and G9 nodes), process complexities intensify, leading to a slowdown in bit growth; third, HBM significantly consumes wafer capacity, severely squeezing the supply of non-HBM products; fourth, limited cleanroom space constrains capacity expansion.
HBM4 Shipments Exceed One Billion, Humanoid Robots and Autonomous Driving Unlock Long-Term Imagination Space
In the forefront of technology monetization, Micron's pace is faster than market expectations. It was revealed at the meeting:
“The high-intensity mass production speed of HBM4 12hi is twice that of HBM3E 12hi, and we have already achieved over $1 billion in HBM4 revenue.”
Micron is strategically aligning its HBM market share with overall DRAM share to balance the demand across the entire market.
In addition to the data center, the realm of Edge AI and endpoint devices is unfolding. In the automotive field, the memory and storage capacity of L2+ and above level autonomous vehicles is over 5 times that of regular cars, and the penetration rate of such vehicles is rapidly increasing.
Even more impactful is the robotics sector. Mehrotra outlined a significant growth blueprint for the market:
“The memory carried by humanoid robots is 10 times that of a regular L2+ level car. We anticipate that in the latter half of this decade, a sustained, substantial, decades-long memory demand cycle will be initiated.”
Full transcript of the Q3 FY2026 Earnings Call:
Sanjay Mehrotra (President and CEO): Micron delivered outstanding performance in Q3 FY2026, achieving significant records in revenue, gross margin, and earnings per share, all above the high end of our guidance. Our data center business revenue exceeded $25 billion in Q3 of this fiscal year, with an annualized run rate surpassing $100 billion, highlighting Micron's position as a leader in the AI era.
Our Data Center SSG business revenue crossed $5 billion, more than doubling sequentially. The demand in the DRAM and NAND industries continues to significantly outpace the industry supply. We expect this tightness to persist beyond the calendar year 2027 due to AI-driven demand across all sub-markets, coupled with structural supply constraints.
We are pleased to announce that we have now signed 16 Strategic Customer Agreements (SCAs), which we expect will fundamentally transform our business model. The memory industry has undergone a structural transformation due to AI proliferation. We are only in the early stages of the significant innovations and productivity that will be unleashed in the future, gradually permeating every corner of the global economy.
Data center-driven growth will increasingly be complemented by AI capabilities in smartphones, high-end PCs, new consumer devices, as well as in the automotive, industrial, and robotics sectors. The exciting possibilities brought by robots, humanoid robots, and fully autonomous vehicles herald a robust long-term demand environment for memory and storage. On the supply front, our customers recognize that the memory and storage shortage will take quite some time to alleviate. While we expect industry supply to gradually improve by 2028, we currently cannot foresee when memory supply will catch up with the continuously growing demand.
The supply growth in the memory industry relies on large-scale wafer fab construction and expansion projects. These new projects are massive, complex, and time-consuming. Furthermore, their progress is constrained by various factors, including the long lead times for global wafer fab construction, a shortage of workers with key process skills, intricate regulations including permits, and the need for enhanced energy infrastructure.
Meanwhile, memory process technology (one of the most advanced and manufacturing-challenging technologies in the semiconductor industry) is becoming increasingly complex with each new node introduction. Technology transitions are slowing down wafer capacity growth over time, significantly increasing the demand for cleanroom space and new wafer fabs. Additionally, the growth of High Bandwidth Memory (HBM) and the improvement in the trade ratio in each new product generation (referring to the relationship between HBM-consumed wafer capacity and non-HBM products) further stress non-HBM supply.
In the NAND domain, industry suppliers are shifting cleanroom space from NAND to DRAM, and the overall limited cleanroom space is constraining NAND bit supply growth. These factors combined mean that despite our comprehensive efforts to increase supply, the growth and the capacity to meet industry demand are structurally constrained.
AI systems are powered by GPUs, ASICs, and CPUs designs from an increasingly broad set of suppliers. However, they all share a critical commonality. The performance of AI systems architecturally depends on the memory subsystem's performance and capacity. This has led to the emergence of a more complex memory hierarchy, providing Micron with a larger differentiation opportunity than ever before.
This elevation of memory's role in the AI world also positions it as a strategic asset. Robust long-term demand growth, structurally constrained supply growth, and the strategic importance of memory are making customers realize that their product roadmaps depend on accessing advanced memory technology and a reliable, long-term memory supply commitment.
Micron has always been an industry leader, pioneering a very robust new type of Strategic Customer Agreement (SCA). We are pleased to announce that we have completed 16 SCAs with customers in the data center, consumer, and automotive markets. These SCAs accelerate the transformation of our business model, strengthen technological and innovative partnerships, and provide customers with contracted supply assurances. Typically, these agreements have a term of five years, running from the calendar year 2026 through the end of the calendar year 2030. Agreements in the automotive space are usually three years in duration. The signed 16 agreements represent approximately 20% of our DRAM sales volume and one-third of our NAND sales volume over this period.
These SCAs include four very large customers and three mid-sized customers. The remaining agreements involve small customers from the automotive industry, representing our commitment to this key sector. Once completed, we expect around half or more of the company's revenue to come from these SCAs covering customers in various end markets.
Our customers value our U.S. supply plan, which is reflected in our Supply Commitment Agreements (SCAs). These SCAs are designed as take-or-pay contracts, comprising commitments to purchase a specific quantity over multiple years. The largest agreements typically have a cap price set at the current second-quarter market price for existing products and a floor price during the agreement term. Several SCAs (a small portion of SCA-related revenue) include fixed pricing or no price range, with pricing subject to market conditions. When all planned SCAs are executed, agreements with fixed pricing or a price cap at or near the current second-quarter market price level are expected to represent approximately 40% of our revenue.
For SCAs that do have price ranges, pricing is intended to remain within that floor to cap range during the agreement term. This pricing visibility will help us better manage business with SCA customers in various market segments and drive their demand. For our SCAs with price ranges, the floor price ensures Micron's very strong gross margin, well above peak quarterly margin in any prior period.
Of the 16 SCAs we have signed, 14, based on minimum contract price calculations, represent approximately $100 billion in revenue over the remaining term of the agreements. These agreements further enhance our long-term financial performance, margin profile, and free cash flow expectations through increased visibility and improved business stability.
Based on SCAs we have signed to date, we expect to receive $22 billion in cash deposits and related financial commitments. This further underscores customer commitment to this new business model. Mark will provide more details. Our SCAs with data center, consumer device, automotive, and industrial applications customers have created a new paradigm for enhancing customer relationships. They provide customers with commitments for DRAM (including relevant HBM) and NAND supply over multiple years. This supply visibility is highly beneficial to customers during times of severe shortage. This visibility enables our customers to leverage SCA supply to advance their strategic plans, drive growth, and ultimately benefit end consumers with their products and services. We greatly appreciate our customers who have worked with us during this time of supply tightness, demonstrating a strong spirit of collaboration to create conditions for long-term mutual success across the ecosystem and for consumers.
The infinite demand for memory bandwidth, capacity, low latency, and low power from AI is driving memory architecture selection, memory product portfolio transformation, and manufacturing technology decisions, all increasing the complexity of the industry's memory and storage roadmap. Micron continues to build on its technology leadership. Our One Gamma DRAM node and G9 NAND node are both ramping production smoothly and are expected to be the highest yielding nodes in Micron's history. Development of our next-generation DRAM and NAND nodes is also progressing well, with production expected to start in the second half of the calendar year 2027. We are applying leading-edge DRAM and NAND nodes across our entire product portfolio. The production ramp speed of HBM4 12-layer high bandwidth memory is twice that of HBM3E 12-layer, and our HBM4 revenue has exceeded $1 billion. We expect HBM4 12-layer to achieve mature yields significantly faster than HBM3E 12-layer. For other highlights on our HBM, high-capacity DDR and server DRAM, data center SSD, PC, smartphone, and automotive product portfolio, please refer to our earnings press release.
We expect future memory demand to continue shifting towards higher-performance, higher-value products, with increased per-chip costs driven by the complexity of these products. The transition from LP5 to LP6, DDR5 to DDR6, and the evolution to the next generation of HBM have all come with rising chip costs. This trend, coupled with the ramp-up of large-scale new capacity over the next few years, is expected to elevate DRAM blended chip costs from current levels. Our customer SCA has provided room for future negotiations on appropriate price premiums for such new products.
Turning to our end markets. AI is propelling unprecedented growth in data centers, with the industry's data center DRAM and NAND bit shipments expected to more than double by calendar year 2026 compared to two years ago. Agent-based AI is reshaping data center infrastructure from the ground up, expanding not only into accelerator-only racks but also encompassing CPU racks for agent control planes and program execution, as well as storage racks for rapidly scaling context memory. We now anticipate that industry server shipments in calendar year 2026 will see growth in the high teens percentage-wise, exceeding our prior low double-digit expectations, driven by both traditional servers' teens percentage growth and stronger growth in AI accelerator servers. We estimate that the uptick in shipment growth expectations is facilitated by a moderate reduction in average server DRAM content growth, as customers focus on maximizing unit shipments in an extremely tight memory allocation environment. In the NAND sphere, AI contextual memory storage and HDD displacement opportunities are expanding SSD's addressable market.
Despite declines in PC and smartphone industry shipments, revenue is expected to grow, reflecting elastic demand for high-value premium devices in the end-device category. Agent-based AI platforms like OpenClo have elevated the value of edge devices, achieving better techno-economics, higher privacy, lower latency, and more efficient AI orchestration between the cloud and the edge. Over time, we anticipate the value of device-side AI plus pent-up replacement demand will drive memory demand growth in PCs and smartphones.
In the automotive field, ADAS (Advanced Driver Assistance Systems) remains a strong driver of content growth. Vehicles at L2+ and higher levels (featuring progressively higher levels of automated driving) have on average over five times the memory and storage content of regular vehicles. The proportion of vehicles at L2+ and higher levels will more than double this year, reaching over 20%, and is expected to exceed 40% by 2030. As the market mix shifts towards higher levels of automated driving (with higher content levels), average memory and storage content per vehicle are expected to further increase.
In the robotics field, the continuous advancement of simulation, base models, and integrated hardware and software stacks is accelerating the development of physical AI. This is creating increasingly rich opportunities to support real-time perception, inference, and control with high-bandwidth, low-power memory, and storage. The memory capacity carried by humanoid robots is 10 times that of a typical L2+ level vehicle, and we anticipate the beginning of a sustained, large-scale decades-long memory demand cycle in the latter half of this decade.
Now turning to our market outlook. We now expect the supply-demand dynamics of DRAM and NAND to remain tight beyond the 2027 calendar year. For DRAM, we anticipate industry DRAM bit shipments to grow in the low to mid-20% range in the 2026 calendar year, slightly higher than our previous forecast. In the NAND space, we expect industry NAND bit shipments to grow by around 20% in 2026, in line with our previous expectations. We expect Micron's DRAM supply growth to be roughly in line with industry supply growth, while Micron's NAND supply growth in the 2026 calendar year will be slightly below industry supply growth. Our SCA enhances our visibility into long-term demand and gives us more confidence in capital expenditures and R&D investments. We are focused on maximizing fab output, including accelerating tool procurement in collaboration with suppliers, fab tool installations, ramps, and tool conversions and upgrades to enhance productivity.
Recently, we have reached a multi-year EUV (extreme ultraviolet lithography) supply agreement with ASML to support the increased application of EUV in our One Delta node and future generations of products. We have also made good progress in expanding our global manufacturing footprint to increase supply over time. This includes significant investments in leading-edge DRAM manufacturing in the U.S., namely our ID1 and ID2 fabs in Idaho, construction of which is progressing well, and our first fab cluster in New York, which broke ground in January of this year. ID1 is expected to yield initial wafers in mid-2027, with ID2 following in late 2028. We recently initiated the first production start of One Alpha DDR4 technology at our fab in Manassas, Virginia, enhancing our ability to support traditional product demand from automotive, industrial, medical, aerospace, and defense market customers. At our newly acquired Taiwan site, we expect meaningful product shipments to commence from the existing 300,000 square foot fab by mid-2027, approximately a quarter ahead of our prior expectations.
In addition to the existing fabs, we have begun constructing a second clean room of similar scale at this site. This clean room will support EUV equipment. Construction activities and timelines at our facilities in Japan and Singapore are also progressing as planned. As a complement to our advanced packaging capabilities in Taiwan, our Singapore site will serve as another advanced packaging center of excellence. We expect this facility to make meaningful contributions to Micron's HBM packaging capability starting in the first half of 2027. While making these investments, we will maintain a disciplined approach and respond to market conditions to adjust our supply plans appropriately. I will now turn the call over to Mark to discuss our financial performance and outlook for the third quarter of our 2026 fiscal year.
Mark Murphy (CFO): Thank you, Sanjay, and good afternoon, everyone. Micron delivered strong results in the third quarter of fiscal 2026, with revenue, gross margin, and earnings per share all above the high end of our guidance. Our performance and today's outlook highlight the increasing value in the AI era and the structural advantages of our business. As stated, we have signed 16 strategic customer agreements. For SCAs with clearly defined pricing (whether fixed or constrained within a range), we have begun disclosing Remaining Performance Obligations (RPO) as of this quarter in May.
At the end of the third quarter of fiscal 2026, RPO exceeded $5 billion. For SCAs already signed, including agreements to be executed after the end of the third quarter of fiscal 2026, RPO is approximately $100 billion. RPO is determined based on minimum committed quantities and minimum pricing and reflects an inherently conservative estimate. RPO does not represent the total revenue we expect to recognize over future periods. Therefore, we anticipate that revenue recognized during the term of the agreements will significantly exceed the associated RPO. As Sanjay mentioned, based on the SCAs we have signed to date, we expect to receive $22 billion in cash deposits and related financial commitments.
The vast majority of these commitments, around $18 billion, will be in the form of cash deposits. As all target SCAs are completed, we expect the level of SCA customer deposits and related commitments to increase substantially. These customer deposits will increasingly appear on our balance sheet in the fourth quarter.
Cash flows related to customer deposits appear in financing activities cash flow and do not impact our free cash flow. This cash will be returned to customers over time in the latter part of the agreement term. We are excited about the progress we have made in signing these SCAs, which will strengthen our long-term financial performance and drive sustained, strong ROI for the company.
Total revenue for the third quarter of fiscal 2026 was $41.5 billion, representing a sequential increase of 74% and a year-over-year increase of 346%, marking our fifth consecutive quarter of revenue records. The sequential increase of $17.6 billion is the largest in our history, surpassing the previous record of $10.2 billion from the prior quarter. DRAM revenue in the third quarter of fiscal 2026 reached a record $31.3 billion, a 343% year-over-year increase, accounting for 76% of total revenue. Sequentially, DRAM revenue increased by 67%. Bit shipments grew in the low single-digit percentage range. Due to industry supply constraints and a favorable product mix, prices increased in the low 60% range. NAND revenue in the third quarter of fiscal 2026 reached a record $9.9 billion, a 361% year-over-year increase, accounting for 24% of total revenue. Sequentially, NAND revenue increased by 99%. Bit shipments grew in the mid-single-digit percentage range. Due to NAND industry supply constraints and a favorable product mix, prices increased in the mid-80% range. The consolidated gross margin for the third quarter of fiscal 2026 was 84.9%, increasing sequentially by 10 percentage points. This improvement was primarily driven by higher pricing, and also benefited from continued strong execution and a favorable product mix. The third-quarter gross margin for fiscal 2026 more than doubled year-over-year, setting a new company record. We now turn to the quarterly financial performance by business segment.
The Cloud Memory Business Unit (CMBU) achieved record revenue of $13.8 billion, accounting for 33% of the company's total revenue. CMBU revenue grew 78% QoQ, driven by higher pricing and bit shipments. CMBU's gross margin was 83%, up 9 percentage points QoQ, benefiting from higher pricing. The Core Data Center Business Unit (CDBU) achieved record revenue of $11.5 billion, representing 28% of the company's total revenue. CDBU revenue increased by 103% QoQ, supported by higher pricing and a favorable product mix. CDBU's gross margin was 87%, up 12 percentage points QoQ, driven by higher pricing.
The Mobile and Client Business Unit (MCBU) achieved record revenue of $11.5 billion, accounting for 28% of the company's total revenue. MCBU revenue grew 49% QoQ, driven by higher pricing partially offset by a decrease in bit shipments. MCBU's gross margin was 87%, up 9 percentage points QoQ, primarily due to higher pricing and a favorable product mix.
The Automotive and Embedded Business Unit (AEBU) achieved record revenue of $4.6 billion, representing 11% of the company's total revenue. AEBU revenue increased by 71% QoQ, supported by higher pricing and increased bit shipments. AEBU's gross margin was 79%, up 11 percentage points QoQ, driven by higher pricing and a favorable product mix.
In the third quarter of the 2026 fiscal year, operating expenses were $1.5 billion, up $97 million QoQ. The QoQ increase was due to variable compensation expense resulting from strong business performance. We achieved $33.7 billion in revenue in the third quarter of the 2026 fiscal year, with an operating margin of 81.2%, up 12 percentage points QoQ and 54 percentage points YoY.
Taxes for the third quarter of the 2026 fiscal year were $5.1 billion, with an effective tax rate of 14.9%. Non-GAAP diluted earnings per share for the third quarter of the 2026 fiscal year were $25.11, up 106% QoQ.
Turning to cash flow and capital expenditures. In the third quarter of the 2026 fiscal year, operating cash flow was $25.4 billion. Capital expenditures amounted to $7.1 billion, resulting in free cash flow of $18.3 billion. Free cash flow in the third quarter of the 2026 fiscal year set a quarterly record for the company. Inventory at the end of the third quarter of the 2026 fiscal year was $8.6 billion, with 120 days of inventory. DRAM inventory remains very tight, below 120 days. Cash and investments at the end of the quarter reached a record $30.2 billion.
In the third quarter of the 2026 fiscal year, we reduced debt by $4.4 billion, including a $4.3 billion reduction in senior notes through a cash tender offer. The weighted average maturity date of our outstanding debt is April 2035. At the end of the quarter, we had $5.7 billion in debt and a net cash balance of $24.4 billion.
In this fiscal year, we have received upgrades from all three major credit rating agencies, reflecting our technology and product position, financial outlook, and the strength of our balance sheet, to BBB+. Our balance sheet has never been stronger, and we expect it to further strengthen even as we increase investment in technology and necessary capacity.
Turning now to guidance. We anticipate fourth-quarter revenue to reach a record $50 billion, plus or minus $10 billion. The gross margin is expected to be around 86%, with operating expenses at approximately $1.65 billion. Based on approximately 1.15 billion shares outstanding, we expect earnings per share to reach a record $31, plus or minus $1. The gross margin outlook for our fourth quarter reflects a meaningful slowdown in the rate of price increases. We anticipate operating expenses for the fiscal year 2027 to increase by around $1 billion as we expand R&D to support unprecedented opportunities in memory and storage. We expect the expense growth to be weighted toward the second half of the year. We anticipate a tax rate of about 15% for the fourth quarter and fiscal year 2026.
Micron continues to invest globally in a disciplined manner to meet customer demand. Reminder that our capital expenditures are net of anticipated government incentives. In the fourth quarter, we expect capital expenditures to be around $10 billion, bringing the full-year capital spending for 2026 to approximately $27 billion. Quarterly capital spending for fiscal 2027 is expected to be higher than the fourth quarter level, with over half of the year-over-year increase in 2027 coming from construction capital expenditures as we bring cleanroom capacity online ahead of long-term demand. We predict another significant increase in free cash flow for the fourth quarter. Effective December 9, 2026 (the two-year anniversary of our final chip deal), we intend to increase capital return. Over time, we plan to return 100% of excess cash to shareholders. Our guidance does not include any potential impact from trade or geopolitical developments. I will now turn the call over to Sanjay for closing remarks.
Sanjay Mehrotra (President and CEO): Thank you, Mark. AI is enhancing the value of memory. Micron, in this environment of supply constraints, is closely collaborating with our customers and suppliers on technology, products, manufacturing, and business strategies. Strategic customer agreements are ushering in an exciting era for Micron. We expect these SCAs to significantly enhance the durability and predictability of Micron's strong financial performance, accelerating the transformation of our business model. I extend my appreciation to the global Micron team members for their unwavering focus on execution in all aspects, positioning Micron as a leader in this new AI era as we continue to advance our mission of accelerating intelligence to enrich life.
Timothy Akuri (Analyst): Hi, Sandeep, I—I think we are all trying to figure out how much revenue is locked in under the downside scenario over the next five years. You mentioned two points, you said 14 out of the 16 SCAs have a cumulative revenue of $100 billion. This roughly means about $20 billion of downside price revenue per year, which is far below the run rate you just mentioned. So this suggests not a lot of revenue is covered by the downside price, but you also mentioned that 40% of the revenue will fall under these SCAs. So could you elaborate on that and help us think through the downside scenario? Can you help us understand how much revenue is guaranteed each year?
Sandeep Mehrotra (President and CEO): As we have pointed out, under these completed SCAs to date, revenue is expected to be $100 billion based on the downside price. But again, as Mark pointed out in his remarks, we expect revenues to be well above this. Note that under the downside price, our gross margin levels are higher than at any previous peak profit levels.
Overall, about 20% of DRAM and about 30% of NAND sales are currently covered by these SCAs. So this represents approximately 25% of our revenue that you can predict over the term of these agreements. Therefore, the RPO is reported as an accounting metric based on the downside price, but we fully expect revenues to be well above this.
Timothy Akuri (Analyst): Got it. Then, regarding how these agreements are specifically implemented, Mark, for example, how much of the revenue for this quarter in August will be under the SA (Strategic Agreement)? I just want to understand how to incorporate it into the model and when you will achieve full run rate, like by the fourth quarter of the next fiscal year, will you have achieved full run rate covered by these SCAs? Can you help us understand this?
Mark Murphy (CFO): Yes, Tim. So you will see a disclosure in the Q that will disclose the next 12 months' revenue associated with each RPO agreement. For example, for those agreements completed in the third quarter, you will see an RPO of $5 billion over the $5 billion. You will see associated future 12-month revenue of about $1.8 billion.
This is because some of these are smaller agreements, such as the automotive sector agreements Sandeep mentioned. Now, in the fourth quarter, as Sandeep mentioned, you will see the 14 agreements out of the 16 reporting an RPO of around $100 billion.
The related revenue for the next 12 months will also be disclosed in the 10-K (annual report). So, you will be able to roughly understand how these have been progressively implemented. Please remember, this RPO figure is the minimum contractually assured amount at the intersection of volume and pricing. Therefore, Tim, what you are seeing is a minimum figure, and it is important to remember that we explicitly state that this does not reflect what we believe will happen. Additionally, this RPO figure will change each quarter. It will vary based on new contracts, may change with additional commitments at determined prices.
It will fluctuate based on shipments and how RPO reduces post-obligation fulfillment. So, you will get a lot of additional reporting. All of this is based on the ASC 606 standard. I know this is something we—typically we do not commonly use this standard in some reports, but with RPO, this feature, you will see.
I also want to emphasize, as Sandeep mentioned, even at the minimum price, ultimately we expect around 40% of revenue to be under these RPO-related commitments. But even at the minimum price, we expect the profit margin to be significantly higher than past peak profit margins.
Timothy Akuri (Analyst): Okay. Thank you both.
Unidentified Participant: I also wanted to ask about LTAs (Long-Term Agreements). Could you talk about the role of cash collateral? Should we view it as a custodial margin account? If a customer cancels, can you then use that cash? If it's not revenue, then what is the significance of this collateral, and how does it relate to RPO (if any)?
Sandeep Mehrotra (President and CEO): Okay, Joe. Regarding collateral, we mentioned that as of this call, we have $22 billion in collateral and financial commitments from agreements signed. Of this, approximately $18 billion is cash collateral. We will receive this collateral. We received over $400 million in the third quarter. We will receive another $10 billion or so in the fourth quarter. These will—yes, these will be considered as cash collateral, will be reflected in financing activities cash flow, will not affect free cash flow. During the commitment fulfillment period of the agreements, they are held by us. As these agreements are fulfilled, these collaterals will be gradually returned over time, but predominantly in the latter part. The difference between $22 billion and $18 billion, about $4 billion, is in letters of credit.
Unidentified Participant: Okay. But what is its purpose? I mean, what happens to this cash? It seems like they put up collateral, and then they get that collateral back. You know, what's the reason they committed this cash? Is this related to some sort of pay-if-not-agree? This is not a prepayment. Could you help us understand?
Mark Murphy (CFO): Yes. Thank you, Joe. This is not a prepayment. This is a separate customer commitment that reflects our binding agreements, and these are letter of credit agreements, we hold cash, which reflects our joint commitment to fulfill these agreements. This is advantageous to Micron, of course, these agreements allow us to see the demand, the quantity of commitment, and we can confidently make investments, large capital investments, to build closer technical relationships. This is advantageous to the customers as they get supply assurance, they get leading-edge technology.
So from our perspective, it's a win-win, and we are very pleased with the nature of the agreements and their impact on the business and as a sign of Micron's business model transformation. Unidentified Participant: Very helpful. Thank you all for your disclosures on this. Really helpful. Thank you.
C.J. Muse (Analyst): Good afternoon. Thank you for taking my question. Perhaps as a follow-up to Joe's question, Mark. When you consider this cash collateral, do you view it as unrestricted cash available for capex? And as part of it, as you think about capital return, especially post the December 14th expiration of the chip act.
Do you plan to include this cash received in your overall cash consideration and capital return consideration? Or, given that you ultimately need to return this cash, does this lead you to think about holding more total cash in a steady state, all else equal?
Mark Murphy (CFO): CJ, this is unrestricted.
C.J. Muse (Analyst): But does it change your consideration for how much total cash you need to feel comfortable holding?
Mark Murphy (CFO): Not in the short term. I think we will certainly have the liquidity that we think is sufficient to support the business operations, that will include over time, as customers and Micron fulfill contracts, returning the collateral. Of course, that's important, but we will hold liquidity to meet what we believe are important investments for the business.
We have a lot—we are undertaking large projects to provide supply, as well as R&D projects. So—I stress again, as I mentioned earlier, customers will get back this collateral in the latter part of the agreements.
C.J. Muse (Analyst): Got it. And perhaps as a follow-up on the HBM revenue. Could you share your views on 2026 calendar year market share and total revenue? And do you expect in the 2027 calendar year, you could get your margin close to the D5 level? Or is this going to be a permanently sub-D5 level area? Thank you very much.
Sanjay Mehrotra (President and CEO): Regarding HBM, first and foremost, we are very pleased with our HBM4 product and the fact that our HBM4 revenue has crossed the $1 billion mark. In terms of HBM market share, we have strategically chosen to bring it close to our DRAM share. This is important because of HBM's trade ratio. As you know, it consumes a significant number of wafers and puts pressure on non-HBM supply in the industry. Therefore, setting our HBM share target close to our DRAM share strategically enables us to serve diverse end-market customers, covering markets such as data center, consumer, automotive, industrial, and others that require non-HBM supply.
Regarding your question about pricing for next year, we do not specifically comment on pricing. However, we can certainly say that HBM is a product where Micron holds a strong leadership position. We have seen tremendous success in HBM3E 8 layers, HBM3E 12 layers, and now with HBM4, and we have a strong roadmap and confidence in execution capabilities.
It is a higher-priced product compared to non-HBM products per bit. And it is crucial for the entire AI ecosystem from the data center to the edge. Therefore, strategically, it is a very important product for us and one that delivers a strong ROI.
Vivek Arya (Analyst): Thank you for addressing my questions. The first question, Sanjay, you mentioned four large and three mid-sized customer agreements. I'm curious how many of them are related to data centers? Should we expect more data center-related announcements? Is the $100 billion aligned with large and mid-sized customers or is it aligned with small customers? I'm trying to understand what a typical data center customer SCA looks like. Have you provided enough clues for us to figure out the situation for data center SCAs over the next few years?
Sanjay Mehrotra (President and CEO): Our large customers include data center customers, and when you refer to large and mid-sized customers, it certainly also includes our small customers, covering data center, consumer, and automotive markets. We have provided relevant information, and large agreements typically have a price ceiling, with a price range setting that ceiling at the pricing level of the current second quarter. As you know, the pricing level in the current second quarter is reflected in our third-quarter performance and fourth-quarter guidance, offering unprecedented profit levels. These price ranges also set a floor price, at which the gross margin is significantly higher than at any peak in the company's historical periods. The large agreements we mentioned are multi-year agreements that provide us with significant demand visibility, customer commitments, and, of course, financial commitments, including the cash collateral Mark detailed earlier.
Vivek Arya (Analyst): Thank you. As a follow-up question, Mark, regarding gross margin, will the 86% level be sustained for a while? Is there a cap? And as these SCAs start to kick in, should we assume some level of normalization, ranging between your current mid-80s level and the peak-high 60s level we've seen before? So, as a long-term investor in constructing models for '27, '28, should they assume a normalized gross margin in the mid-70s range, between your current level and the peak? If you could provide some guidance on how to think about the recent 86% gross margin and how these margins unfold in the long term, that would be appreciated. Thank you.
Mark Murphy (CFO): Yes, Vivek, we do not provide guidance beyond the fourth quarter. But at the margin level we're at, as we've discussed before, the diminishing returns of gross margin expansion from incremental price increases will come into play. Nevertheless, as we've mentioned, we've updated our view of the market, and we expect the market to remain tight post '27.
We are currently in a phase where memory is highly valued as a strategic asset, valued for enhancing AI intelligence and the need for more and higher-performance memory. Therefore, we continue to deploy capacity toward higher-performance applications such as data center and edge devices, which will help us optimize capacity allocation with customers as price increases decelerate, including with customers under these SCAs. Additionally, as mentioned, we will start to see significant additional output in '27 and growth into '28. There will be some ramp costs, but as these ramps progress, we will absorb them. Thus, over time, we will gain operating leverage.
Yes. So I think we feel really good about the trajectory of the business, Micron's technical position, the world-class product portfolio, and you can see we're executing very well, all of which contribute to our continued delivery of strong financial performance.
Krish Sankar (Analyst): Yes, hi. Thank you for addressing my question. I have two questions, Sanjay or Mark. Congratulations on the outstanding performance. Regarding LTAs (Long-Term Agreements) floor pricing, you mentioned it's approximately at the previous peak gross margin level or some level just above 60% (around 62%). If I try to estimate a 64GB server DRAM price, I might get around $700, whereas today it's $1500, which roughly means a floor of around $10 to $12 per GB and the current price is around $20 per GB. Is this the range we should consider for these LTAs, i.e., a pricing range of low teens to mid-twenties per GB is the LTA pricing range to consider per GB?
Sanjay Mehrotra (President and CEO): Krish, we won't go into specific pricing discussions, but I just want to reiterate that I stated the gross margin at the lower end price would be significantly above the peak points we had experienced in past cycles, those historical peaks. So well above those, right? But we're clearly not going to disclose specific pricing-related details.
The bottom line is, these SCAs have indeed helped provide us with visibility, strength, and resilience in meeting demand. They have absolutely accelerated our financial performance and business transformation at the core.
Krish Sankar (Analyst): Understood. Very helpful, Sanjay. And then quickly following up, you mentioned DRAM should be up low-to-mid 20s this year, NAND up roughly 20%. Clearly, both are supply-constrained. Any way to quantify what happens in 2027? Any way to say, will the supply-demand imbalance in 2027 be double of this year, or how to think about the supply-demand imbalance in 2027?
Sanjay Mehrotra (President and CEO): We anticipate tightness overall in 2027. We have indicated that we expect the tightness to persist beyond 2027, and we are working hard to add supply, but we have shared with you that it takes a long time to bring on the incremental capacity, additional wafer capacity needed to meet customer demand, of course, the technology transitions, the lesser bit growth per generation node, and the HBM trade ratio have all put substantial pressure on overall supply growth.
So, supply—even as we look to see some easing in 2028, we expect demand to remain on a strong trajectory as these AI trends are very long-term trends. AI is still very, very early stage. The entire tokenomics (referring to AI model processing costs) requires more memory. AI system performance is actually memory capacity, memory performance, memory bandwidth lagged.
Therefore, with the growth in compute demand, and our customers seeing massive transformation opportunities ahead of them, their need for memory will continue to invest in building infrastructure like they have never before as a result. The demand trajectory is incredibly robust. Our memory sits at the heart of that, it is a strategic asset, and securing memory supply is clearly a critical priority, you can see that from our multi-year agreements signed with customers. I mean, those agreements reflect their confidence in demand growth. So, we are working hard to add supply, but we expect tightness to persist beyond 2027.
Join the official Coincamps community:
Telegram: https://t.me/coin_camps
Recommended
Desk: Brent Crude Tops $110, Musk's Net Worth Drops 528.6 Billion in Four Days After Tesla Roadster Launch
Oct 17, 21:49
JST Fifth Buyback and Burn Successfully Concludes: Over 170 Million Tokens Worth Approximately $23.53 Million Burned, Buyback Mechanism Set for Comprehensive Upgrade
Oct 17, 20:10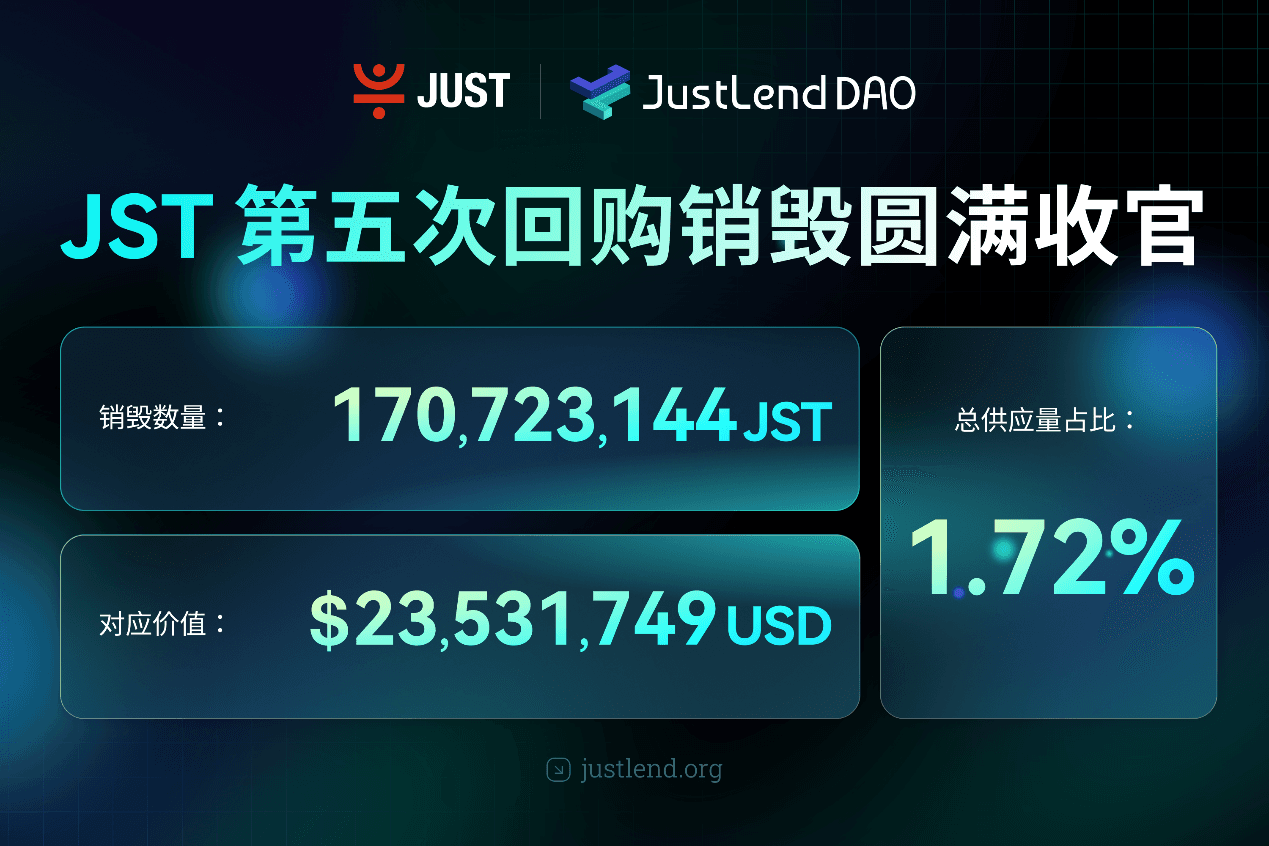
BitTorrent Brand Upgrade and Initial BTT Buyback & Burn Launch Simultaneously, Dual Engines Usher in New Era of Web3 Infrastructure
Oct 17, 20:00
Asia Market Daily: Japan's BOJ signals more rate hikes while Korea targets offshore perpetual platforms (2026/10/17)
Oct 17, 17:01Why did Papertrade backfire on you?
Oct 17, 17:01
The 'Strict Father' of Northern Myanmar: This Company Deploys 200,000 "AI Best Actors" to Strike Back Against Scammers
Oct 17, 15:34