Nomura Raises Target Price for Unisoc, Can the $1.6T Optoelectronic Module Support a 20% Upside?

TL;DR
· Nomura raised InnoLight's target price from ¥1015 to ¥1325, still implying a 20.6% upside from the July 6 closing price.
· The target price is based on a ¥66.06 EPS for 2027 and a 20x PE ratio, betting on 1.6T and higher-speed optical module mass production.
· This forecast is significantly higher than the Wind consensus, with supply chain bottlenecks, customer demand fulfillment, and repeat orders still posing risks.
According to a Securities Times report on July 7, Nomura has maintained a "Buy" rating on InnoLight and raised the target price from ¥1015 to ¥1325. Based on InnoLight's closing price of ¥1098.92 on July 6, the new target price implies approximately a 20.6% upside.
The key change in this revision lies not in the valuation multiples but in the profit forecast. Based on the report's data, the ¥1325 target price is derived from an EPS of ¥66.06 for 2027 and a 20x P/E ratio. A 20x P/E ratio is roughly in line with the median level of the Wind China A-share technology and electronic components sector, while InnoLight currently corresponds to approximately 16.6x 2027 forecast P/E.
For investors, the report truly elevates the demand ceiling for AI data center optical modules. InnoLight's core story still revolves around the high-speed optical module upgrade, from 800G to 1.6T, then to 2.4T, 3.2T, and the further NPO/CPO forms. Nomura's assessment is that this upgrade path will position the company's revenue and profits post-2027 significantly above the market consensus.
According to the report's data, InnoLight's revenue forecast for the FY2027 has been raised to ¥261.031 billion, with net profit attributable to the parent rising to ¥73.396 billion. The adjustments for 2028 are more significant, with revenue forecast raised to ¥371.545 billion and net profit attributable to the parent forecasted at ¥103.944 billion.
This is not just a bet on short-term order improvement but an overall advancement or amplification of the mass production pace of higher-speed products from 2027 to 2028.
The profit margin assumptions have also been increased. The report raised the gross margin forecast for FY26-28 to 45.7%-46.2% and kept the operating margin around 34.5%-35.0%. The rationale behind this is that after the increase in the proportion of 1.6T, silicon photonics, and other high-end products, the product mix improvement can offset some price pressure.
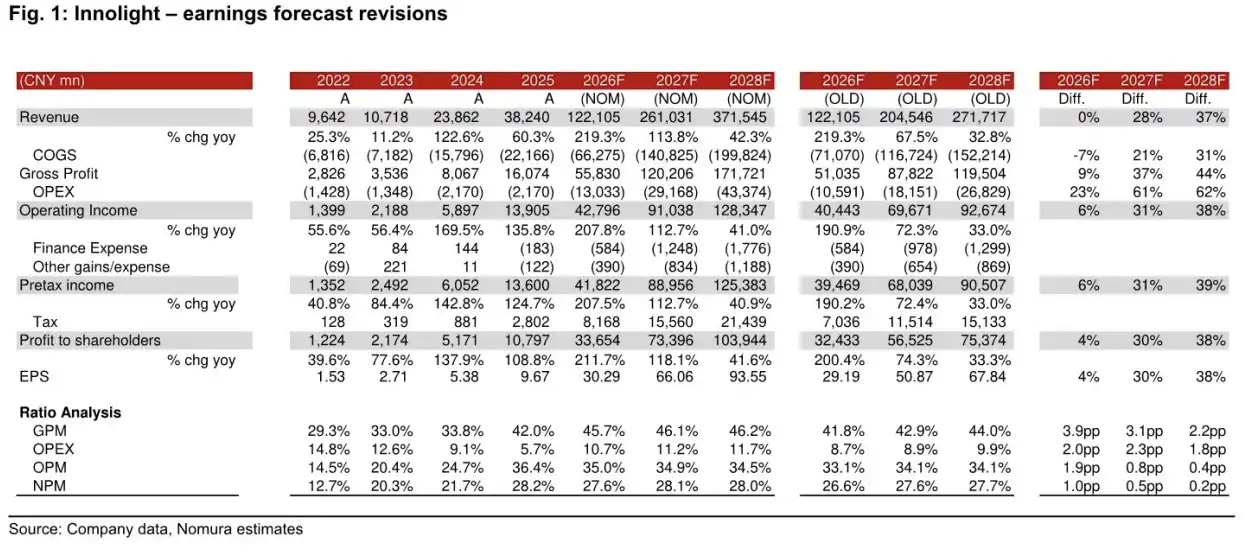
Revision of FY26-28 Revenue, Net Profit, and Gross Margin Forecast, with a target price of ¥1325 as the main basis.
The direct source of the target price increase is also here. The valuation multiple remains unchanged, still calculated at 20 times the 2027 EPS. What has changed is the 2027 EPS, which has been raised from the previous ¥50.87 to ¥66.06. The ¥1325 target price mainly comes from the increase in profit forecast, rather than a more aggressive valuation.
The biggest assumption supporting the profit increase is that AI data center high-speed optical module shipments will continue to rise.
Based on the source report's data, global 800G optical module shipment forecasts have been raised to 55 million units in 2027 and 78 million units in 2028. The 1.6T shipment forecast has been raised to 71.5 million units in 2027 and 126 million units in 2028. More importantly, the report has for the first time included the assumption of higher-speed products, with 2 million units of 2.4T shipments in 2027, 5 million units of 2.4T shipments in 2028, and 2 million units of 3.2T shipments.
These numbers correspond to the continued expansion of cloud vendor AI clusters. After the increase in GPU quantity, the demand for high-speed optical modules in inter-server, inter-rack, and intra-data center networks has simultaneously increased. For optical module manufacturers, a rate upgrade usually means higher unit prices, technological barriers, and customer certification thresholds, making it easier for leading manufacturers to pull ahead.
Nomura predicts that Jiangsu Aucksun is expected to maintain a 30%-35% share of the global AI data center optical module market. If this market share assumption holds true, the industry's shipment volume increase will directly translate to the company's revenue. If the proportion of high-end products increases smoothly, the profit margin will also be supported.
The discrepancy lies here. Based on the source report, Jiangsu Aucksun's FY26-28 revenue forecast is 32%-67% higher than the Wind consensus, and net profit forecast is 14%-38% higher. The 2027 revenue forecast is ¥261 billion, while the Wind consensus is about ¥163.6 billion. By 2028, revenue forecast is 67% higher than the consensus, with net profit up by 38%.
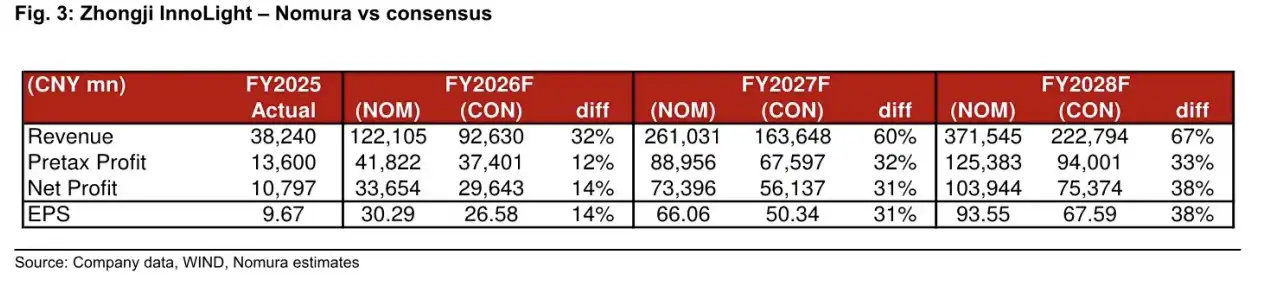
Comparing Nomura with the Wind consensus shows that the revenue forecast for 2027 is 60% higher than the consensus, and the revenue forecast for 2028 is 67% higher than the consensus.
The $1325 price target reflects a more optimistic outlook than the market average, based on demand, market share, and product upgrade assumptions. Whether it can be achieved depends on whether large customers continue to increase AI capital expenditures and if the product transition after 1.6T progresses as expected.
Post 1.6T, NPO and CPO are seen as sources of continued growth post-2028.
In simple terms, traditional pluggable optical modules face challenges in power consumption, bandwidth density, and heat dissipation as AI cluster scale increases. NPO and CPO aim to bring the optoelectronic conversion module closer to the switching chip, reducing transmission losses and improving overall efficiency. If this architecture is widely adopted, leading optical module manufacturers may still be involved in new product forms and supply chain division of labor.
Adding NPO/CPO to the long-term growth narrative indicates that the growth story goes beyond the 1.6T milestone. With advancements to 2.4T, 3.2T, and new packaging forms, there is still room for upward revenue growth post-2028.
However, this cannot be presented as a foregone conclusion. NPO/CPO still involve issues such as customer architecture choices, switch chip coordination, thermal management, yield, and costs. Even with a clear technical direction, the pace of scalable adoption may be slower than optimistic assumptions. For stock price, these long-term products are more like valuation support rather than recognized revenue on the financial statements.
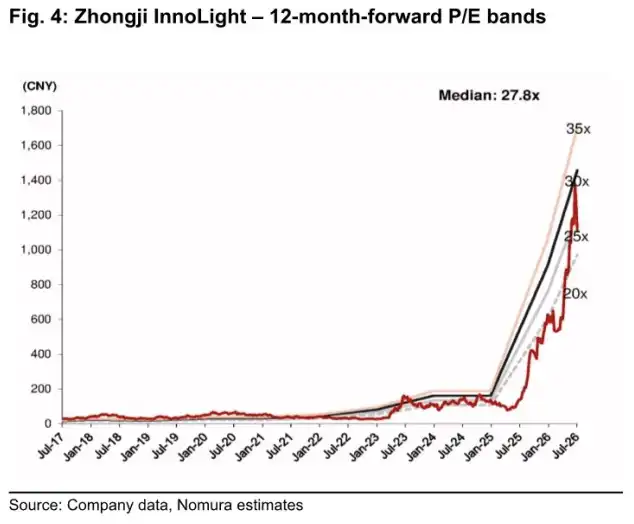
12-month forward P/E multiple range chart, can be used in conjunction with the $1325 price target and a 20x 2027 PE assumption.
Short-term constraints are primarily in the upstream supply chain.
InP wafers, MOCVD equipment, 200G EML, and other links may still face tightness, driven by yield ramp, equipment delivery cycles, and supply chain disruptions. Public reports mention that Nomura Securities expects II-VI's second-quarter earnings in 2026 to increase by approximately 20%-22% QoQ. However, whether the supply chain can sustain higher shipments will still impact short-term performance realization.
In the long term, capacity expansion may alleviate some shortages. JX Advanced Metals announced on June 16th a plan to invest up to ¥120 billion over the next four years to expand InP substrate capacity, combining with existing investment plans, targeting a capacity around 7-10 times that of FY2025 by around FY2030. However, there is still a time lag from capacity planning to stable supply, and high-end materials and devices still need to undergo yield improvements, customer certifications, and scale delivery validations.
Another risk is duplicate orders. During the AI infrastructure cycle, there is a risk of customers allocating inventory ahead of time, placing duplicate orders, or suppliers overestimating real demand during a peak demand phase. Once cloud providers adjust their capital expenditure pace, order visibility may change rapidly, leading to inventory and price pressure upstream.
The significance of the ¥1325 target price does not necessarily mean the stock price will rise by another 20%, but rather it reflects Nomura's optimistic valuation based on increased shipments, a better product mix, and higher EPS by 2027. InnoSunny continues to be one of the most prominent core targets in the AI optical module chain, but the current divergence has narrowed down to one question: post-1.6T demand and profit margins, whether they can be realized at a more aggressive pace than the market consensus.
Join the official Coincamps community:
Telegram: https://t.me/coin_camps
Recommended
Desk: Brent Crude Tops $110, Musk's Net Worth Drops 528.6 Billion in Four Days After Tesla Roadster Launch
Oct 17, 21:49
JST Fifth Buyback and Burn Successfully Concludes: Over 170 Million Tokens Worth Approximately $23.53 Million Burned, Buyback Mechanism Set for Comprehensive Upgrade
Oct 17, 20:10
BitTorrent Brand Upgrade and Initial BTT Buyback & Burn Launch Simultaneously, Dual Engines Usher in New Era of Web3 Infrastructure
Oct 17, 20:00
Asia Market Daily: Japan's BOJ signals more rate hikes while Korea targets offshore perpetual platforms (2026/10/17)
Oct 17, 17:01Why did Papertrade backfire on you?
Oct 17, 17:01
The 'Strict Father' of Northern Myanmar: This Company Deploys 200,000 "AI Best Actors" to Strike Back Against Scammers
Oct 17, 15:34