
Correctly Forecasting the Grand Decade-Long AI Narrative, But Crushed by Leveraged Liquidations: The $10 Billion Wipeout of Wall Street's "Current Favorite" Leopold
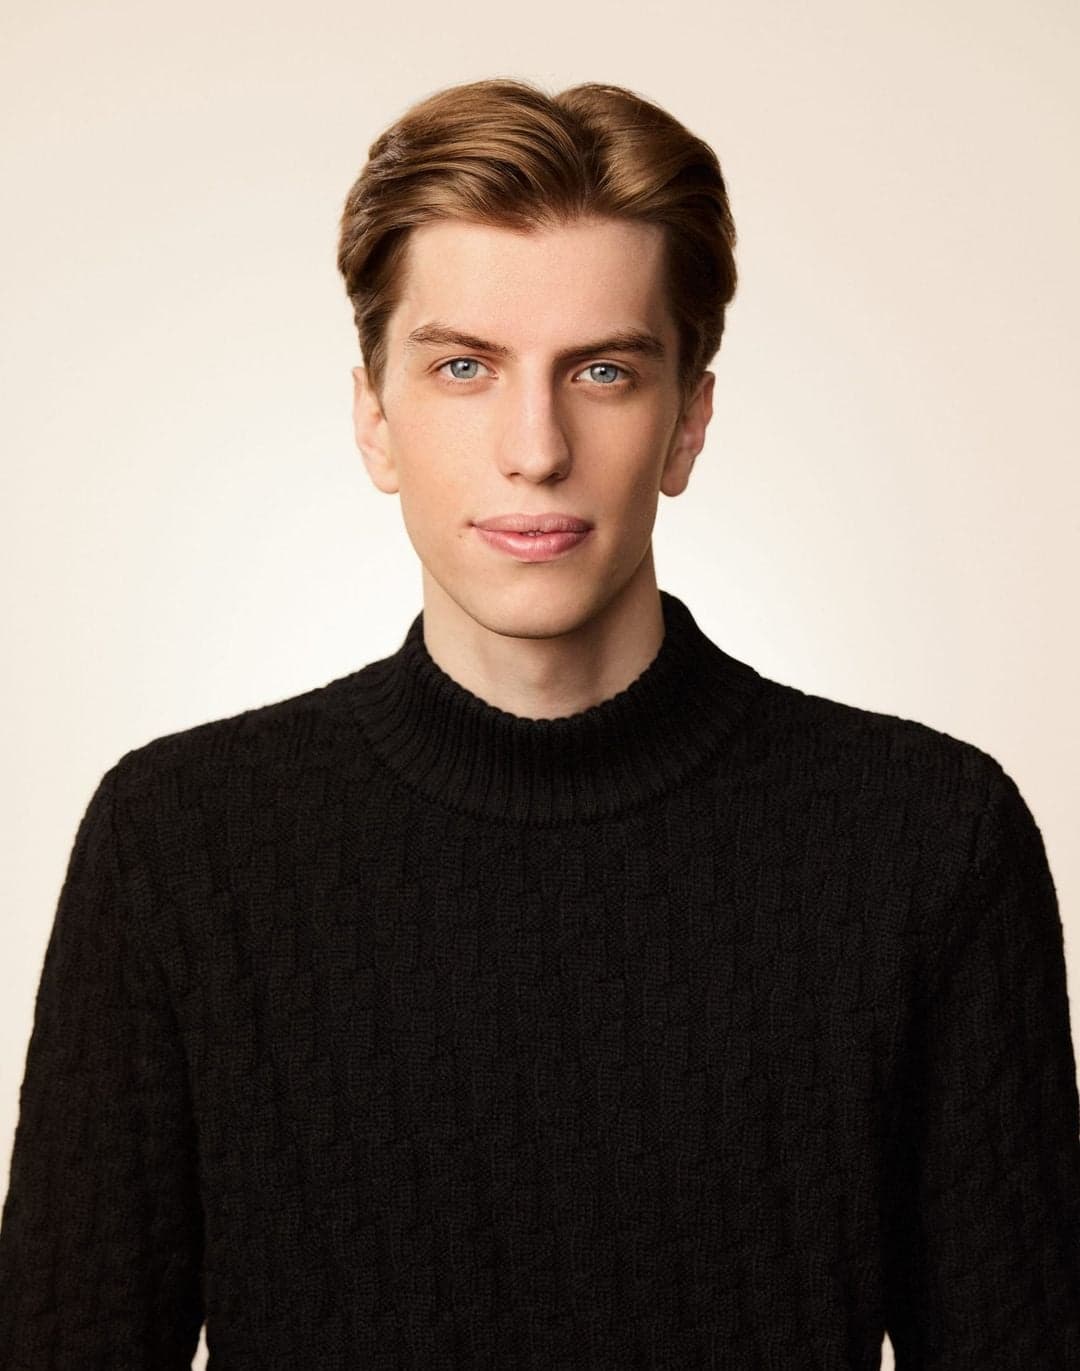
AI stocks plunged again, and the market once again remembered the young man who walked out of OpenAI and made his name by betting on computing infrastructure.
Leopold Aschenbrenner, known as the "market darling" in Chinese investment communities. In July this year, his fund portfolio dropped 67% in a single month; in September, he began trading options again. Now, that familiar batch of stocks is facing another wave of selling, with headlines declaring he has "been liquidated again."
The once-market darling has nearly turned into an abandoned choice as stock market fortunes shifted dramatically after the Democratic Party won the midterm elections.

He Buys Whatever AI Needs
Leopold's investment story is easy to believe.
He previously researched superintelligence safety at OpenAI. After leaving, he founded an investment firm, attracting early backers including Stripe's Collison brothers, Nat Friedman, and Daniel Gross. This background places him squarely between two camps: those researching how far AI will actually go, and those with capital betting on it reaching that distance; and he clearly possesses both.
His stock selection was equally straightforward. AI needs more storage, so Micron and SanDisk entered the portfolio; model training and inference require compute power, with Nebius and CoreWeave providing cloud services; data centers need electricity and server space, with Bloom Energy and Core Scientific also appearing in his holdings.
While these companies do different things, their revenues are tied to the same expense: building and operating more AI infrastructure. Rather than guessing which model will ultimately win, buying the hardware they must procure appears to be a more intuitive and widely believable investment strategy.
The money was indeed made. According to an investor letter disclosed at the end of July, the fund achieved a net return of 439% in the first half of the year. By late June, publicly reported US equity holdings showed SanDisk and Micron combined for roughly 55.6%, meaning these two storage alone accounted for over half. Although other companies in the portfolio offered sector diversification, none removed the fund from the AI construction boom.
During the rally, this concentrated bet amplified returns and fueled the hype around having an early grasp of the AI narrative, youthful promise, and proximity to the core circle, pushing the deification atmosphere to its peak.
But by July, chip stocks came under heavy selling pressure. Because the fund utilized high leverage, margin calls arrived quickly. At month-end, it sold most of its listed equity positions to Citadel. An investor letter seen by Reuters showed his portfolio fell 67% that month. Leopold began apologizing, writing in a letter to investors: "We disappointed you this month."
However, even accounting for this loss, the fund still rose approximately 80% for the full year.
The Stocks He Sold, The Buyers Didn't Plan To Hold Long Either
After Citadel took over the positions, it quickly began breaking them up and selling them off.
This was no Wall Street titan pouring faith into AI's boundless future; it was a brutally cold-blooded sale of distressed assets. Citadel CEO Ken Griffin acted here as an emotionless clearinghouse machine. In less than three weeks, through hundreds of block trades, he rapidly offloaded over 80% of the original portfolio's risk, cashing out more than $4 billion.
As this top hedge fund boss emphasized in his letter to investors: "The ability to fragment and dispose of these risks is what makes this transaction viable."
To retail investors, the same batch of stocks represented the future of AGI, while Wall Street old money saw only price spreads on blood-stained chips. Buyers had the capital to take positions and quickly dump them; sellers only survived precisely because they were forced to lay down all their cards.
Felled by a "Policy Black Swan" Post-Election
Although he survived the July liquidation by cutting his losses, in the financial system, cracks spread rapidly once they appear.
In September, due to an extremely poor risk management record, JPMorgan officially cut off lending services to the Situational Awareness Fund. This meant Leopold lost Wall Street's most critical credit engine.
However, this former OpenAI research prodigy did not give up. Stripped of direct margin financing, he pivoted to the options market in mid-September, aggressively buying call options on infrastructure stocks like AMD, Bloom Energy, and CoreWeave.
In pursuit of extreme leverage, he even bought deep out-of-the-money (OTM) options, attempting to use this "do-or-die" tool to make a lone rescue, betting that stock prices would experience an explosive moonshot rally in the short term.

He tried to use options to catch the second half of the AI frenzy, but collided head-on with the iron wall of policy following the November midterm elections.
As the Democrats swept control of both chambers, multiple U.S. states flipped red lights on data centers, triggering a brutal revaluation of AI infrastructure stocks. From June highs to November 5, CoreWeave plummeted 65%, Core Scientific dropped 60%, and SanDisk and Micron were also severely wiped out.
If Leopold had held spot positions, a 60% plunge might have been survivable until the end, trading time for AGI's potential upside; but he held options with severe time decay.
Under the dual squeeze of crashing underlying assets and approaching expiration dates, the remaining value of this bet was effectively ruthlessly zeroed out.
Leopold's exit serves as the most profound metaphor of this frenzied era:
He bought everything AI had to spend, and his macro direction may have been flawless. But his—and many other investors daring enough to leverage up or go all-in on AI's future—greatest fallacy lies in trying to fully capture a grand blueprint that takes a decade to materialize, using high leverage and short-term options constantly threatened by forced liquidation.
The starry sea toward AGI remains vast, but this most devout evangelist has already perished in the leverage before dawn.
Join the official Coincamps community:
Telegram: https://t.me/coin_camps
Recommended
After Robinhood, perhaps it's Elysium's turn.
Nov 6, 16:10
Nearly $200 Million in Lobbying Goes Down the Drain: Washington Turns, and Crypto Faces Headwinds
Nov 6, 16:10Immutable Announces Transition to Ethereum Rollup: Migration to OP Stack in 2027, Block Time Reduced to 1 Second
Nov 6, 16:01
Wall Street Hedge Funds Buckle as the Biggest Deleveraging Wave in Over a Decade Hits
Nov 6, 15:10October 2026: USDD Monthly Transparency Report
Nov 6, 15:01
Safe-haven sectors may also be sold off; why is it hard to avoid rotation in US stocks this time?
Nov 6, 14:46