
3-month valuation surges 6x, is OpenRouter worth $7.5 billion?
On August 19, 2026, Stripe announced an acquisition agreement with OpenRouter, its largest acquisition to date. The two sides did not disclose the final consideration; media reports put the range at roughly $7 billion to more than $8 billion, with The New York Times citing about $7.5 billion. Compared with the roughly $1.3 billion valuation in its Series B 83 days earlier, that amounts to a nearly 6x repricing in less than three months.
What OpenRouter does is not complicated: it converges 500+ models and 80+ compute providers behind a single OpenAI-compatible interface. It successfully proved one thing—inference demand can be aggregated, and at very large scale. But it also exposed a structural contradiction: protocol standardization is precisely what lets customers leave by changing one line of the base URL. So the real question in this deal is: Can it convert portable order flow into non-portable model intelligence?
Core Views / KEY TAKEAWAYS
▪Value and moats come from the same trend: Rising model substitutability amplifies the value of multi-model selection and dynamic routing, which is the foundation of OpenRouter's existence; but gateway interoperability is strengthening in tandem, driving developer switching costs to freezing point—OpenAI compatibility means any alternative can be plugged in instantly. The same force is both a tailwind and a headwind.
▪The supply side is a real market, but not an exclusive moat: The same model on OpenRouter is bid on by more than a dozen inference providers competing side by side, with significant differences in price, throughput, and availability, and the availability gains from multi-provider redundancy are measurable. But the same set of providers also connects to competing gateways such as Vercel—multi-homing is the norm. Compute liquidity is therefore a proven market utility, not an exclusive moat.
▪Under the squeeze of "zero markup," a take-rate model struggles to support a high valuation: Cloud vendors and platform players are entering the competition by treating basic routing as free infrastructure, monetization per token continues to come under pressure, and pure channel take rates struggle to support a P/S above 40x.
▪Stripe is betting on the leap from "pipe" to "control point": The acquisition aims to connect "model routing + telemetry data + Agent identity/budget/settlement." Whether it can evolve from replaceable middleware into an inseparable Agent transaction control point is the key to the success or failure of this round of betting.
01 /What Is OpenRouter: Problems, Customers, and Products
▍1.1 What it solves is not just "one API to multiple models"
What OpenRouter solves is not merely the convenience issue of "one API to multiple models," but the continuous dynamic management by AI Builders of model selection, vendor scheduling, availability, latency, cost, and data strategy in an extremely fragmented inference market. As the number of models surpasses one hundred, frontier performance frequently shifts, and Token prices continue to deflate, tightly binding an application to a single model has become a major hidden risk—this not only means suboptimal costs and single-point failure risk, but also the loss of the ability to quickly migrate when new models are released.
▍1.2 The real customers are AI builders, not ordinary AI users
OpenRouter's disclosed monthly processing volume of over 400 trillion+ Tokens, 10 million+ global users, 80+ vendors, 500+ models, and 250,000+ applications covering 4.2 million+ end users—clearly reveals its true B2B2C structure: OpenRouter is positioned between developers and their downstream end users, rather than directly facing ordinary AI consumers.
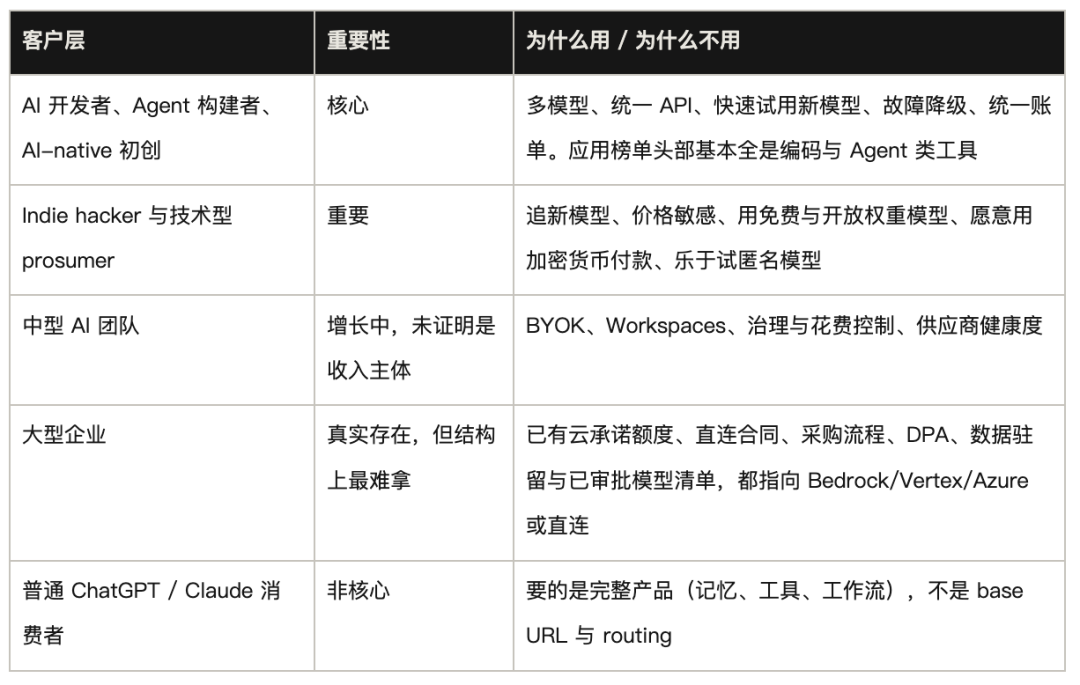
"More and more people are using AI" is almost certain to hold true, but this portion of traffic growth can completely bypass OpenRouter. Under the "humans choose products" model, users independently choose to use ChatGPT or Claude, routing occurs in the human brain, and what is purchased is a complete end-to-end application, so OpenRouter's value is not high; only when the market shifts to the "software chooses models" model, that is, when Agents automatically match the best model, compute vendor, price level, and latency in real time each time they execute a task, can OpenRouter's value be maximized.
▍1.3 Product Stack: Starting from the Gateway, Value Lies in the Top Two Layers
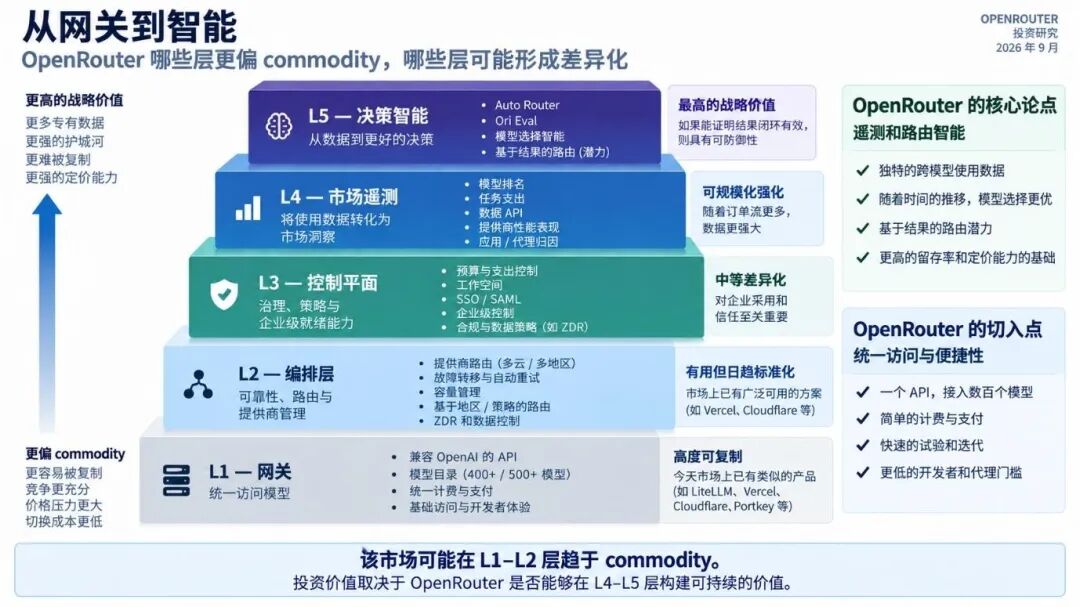
Figure 1 OpenRouter Product Stack L1–L5.
OpenRouter entered the market through the gateway, but its valuation premium and investment thesis are entirely built on the data and decision layers. L1 Gateway, L2 Orchestration, and L3 Control Plane have become highly commoditized, reduced to basic table stakes in the赛道; L4 Market Telemetry and L5 Decision Intelligence are the only battlegrounds for building differentiation and pricing power.
▪L1 Gateway: Provides an OpenAI-compatible unified API, unified billing, and rapid trial access to hundreds of models. Extremely low replication difficulty; competitors (such as LiteLLM, Vercel, Portkey) can replace it instantly.
▪L2 Orchestration: Handles multi-cloud/multi-region failover, automatic retries, capacity management, and dynamic compute routing. Although practical, it has gradually become a standardized feature of open-source middleware and cloud providers.
▪L3 Control Plane: Covers budget control, workspace management, SSO/SAML, and ZDR (Zero Data Retention) and other enterprise-grade compliance controls. A moderately differentiated feature and a passport to entering mid-to-large enterprises.
▪L4 Market Telemetry: Converts massive usage into business intelligence, including industry rankings, task-level spending, compute provider performance, and App/Agent attribution. Its value strengthens with order flow scale and is the cornerstone of OpenRouter's scale effect.
▪L5 Decision Intelligence: Extremely high strategic value, the key breakthrough for the moat. Aims to transform telemetry data into better model selection and outcome-aware routing, directly driving R&D and commercialization ceilings.
02 / How High Is the Market Size Ceiling?
▍2.1 Five Types of Control Points in AI Inference Services
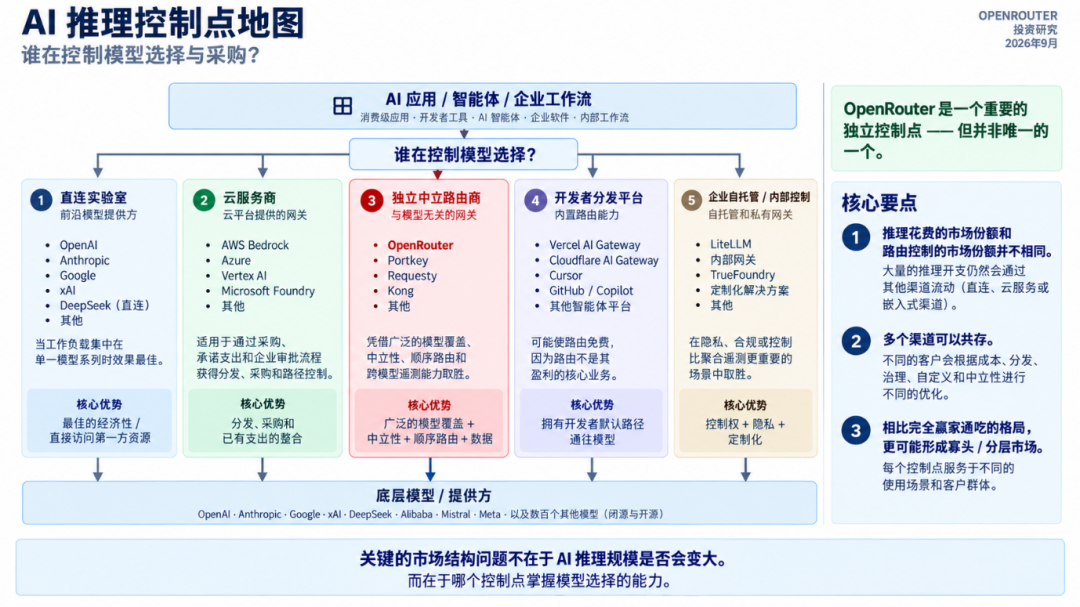
Figure 2: AI Inference Control Point Map.
Between AI applications and underlying models, the five major control points for model selection present a clearly differentiated landscape: Direct OEM connections lock in dedicated workloads through the extreme cost-efficiency of a single model family and native priority access; hyperscale cloud providers dominate enterprise procurement by leveraging existing cloud commitment credits, channels, and compliance approvals; independent neutral routers (such as OpenRouter) aggregate order flow through full-model breadth, neutrality, and cross-model telemetry data; developer distribution platforms treat routing as a free bundled feature by controlling default workflow entry points; while private/self-built gateways dominate in scenarios with extremely high data privacy and deep customization requirements.
▍2.2 Market Size: Not All AI Inference Volume Flows to Independent Routers
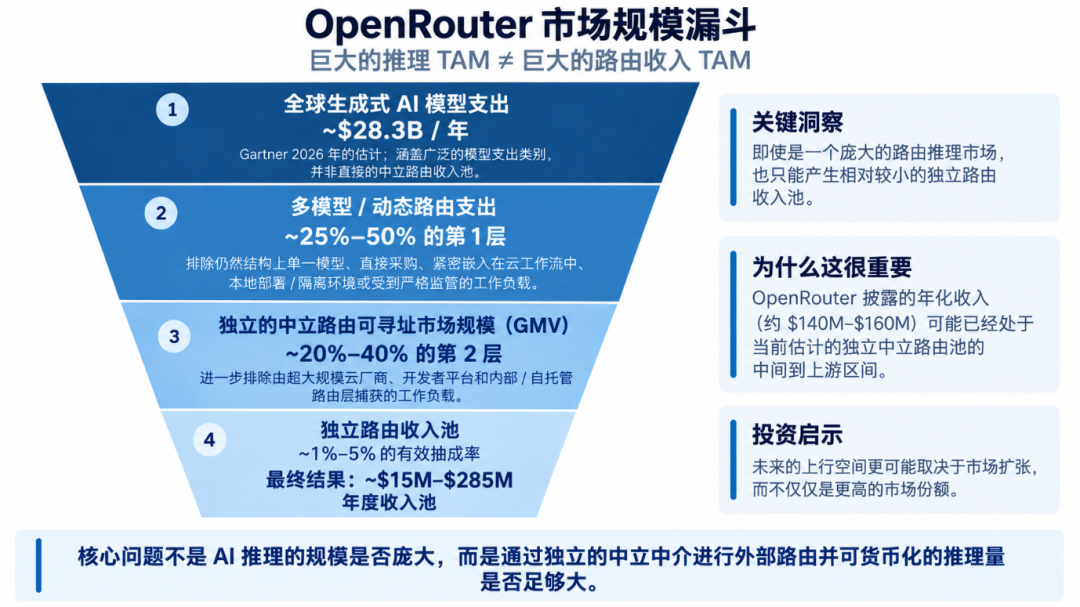
Figure 3: Market Size Funnel (Bottom-Up, Based on Gartner 2026 Estimates).
A massive volume of AI inference does not equal a massive independent routing revenue pool. According to Gartner estimates, global generative AI model spending in 2026 will be approximately $28.3 billion; after deducting single-model direct connections, cloud provider workflows, and enterprise self-hosted solutions layer by layer, the market truly accessible to independent neutral gateways amounts to only $1.4–5.7 billion; further accounting for factors such as BYOK, free discounts, and zero-markup competition (effective take rates of 1%–5%), the actual revenue pool for independent routing is substantially narrowed to $15–280 million (with a midpoint of approximately $60–150 million). OpenRouter's current third-party-estimated annualized revenue of $140–160 million has already entered the upper-middle range of this estimate. If the above assumptions broadly hold, future growth will increasingly depend on expansion of the revenue pool itself, rather than solely on market share gains.
03 / Why OpenRouter Won
If gateway technology is easy to replicate, why did it become the category leader? The answer lies not just in the product, but in the sequence.
▍3.1 The Liquidity Flywheel Is Proven, the Intelligence Flywheel Is Forming
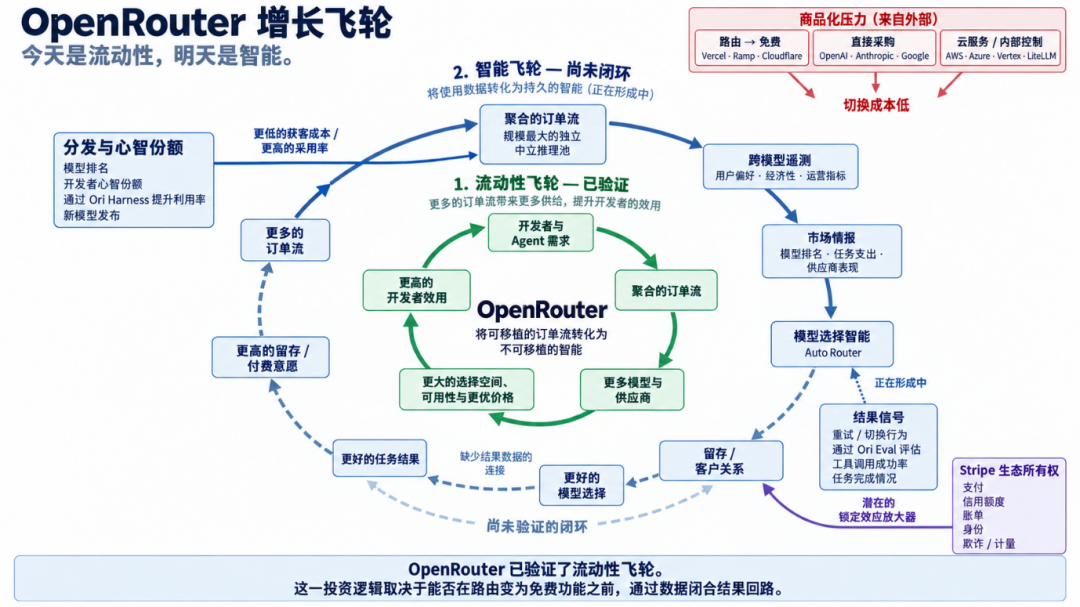
Figure 4: Two Flywheels: The green loop has been proven; the blue dashed segments have yet to be proven.
The chain of the Liquidity Flywheel is: demand from developers and Agents drives order flow aggregation, which in turn attracts more model and compute providers to join, bringing richer choices and price advantages, enhancing developer utility, and forming a positive closed loop. OpenRouter's billing and metered usage demonstrate explosive momentum—weekly Token processing volume grew from 5 trillion in November 2025 to over 55 trillion by August 2026 (averaging over 10 trillion daily), a more than 10x increase in nine months.
The chain of the Intelligence Flywheel is: aggregated order flow precipitates cross-model telemetry data and market intelligence, which in turn feeds back into model selection intelligence (Auto Router). However, the data feedback chain from "better model selection to better task outcomes" still lacks a key closed loop, and its effectiveness has not yet been fully proven.
▍3.2 Mindshare Lowers Customer Acquisition Costs, but Does Not Raise Switching Costs
Comparison page headlines from third-party gateway competitors are universally "OpenRouter alternatives," rather than the reverse. This is the standard linguistic signal of a category default. But what it lowers is customer acquisition cost, not churn rate. OpenAI compatibility means the migration action is changing a base URL and a key. Category default makes it easier for OpenRouter to win new projects, yet barely prevents old projects from leaving.
▍3.3 OpenRouter Is Simultaneously a Launch and Discovery Venue for Models
Emerging labs can release free or anonymous preview versions into a massive pool of real developer and Agent traffic, collect usage feedback, gain leaderboard visibility, and reveal their identity once demand takes shape. Xiaomi's Hunter Alpha and Z.ai's Ox Alpha both completed cold starts this way. For model providers that do not yet have large-scale developer distribution, OpenRouter is a particularly valuable global discovery and cold-start channel. What this reinforces is a distribution advantage, not an exclusive supply moat.
04 / Product Economics and Business Model
What exactly are customers paying for? The company explicitly does not mark up inference prices and passes through supplier pricing; the 5.5% is a platform fee when purchasing credits, and BYOK free quota is measured by amount rather than number of requests. The real question is: under what conditions does this fee start to become uneconomical.
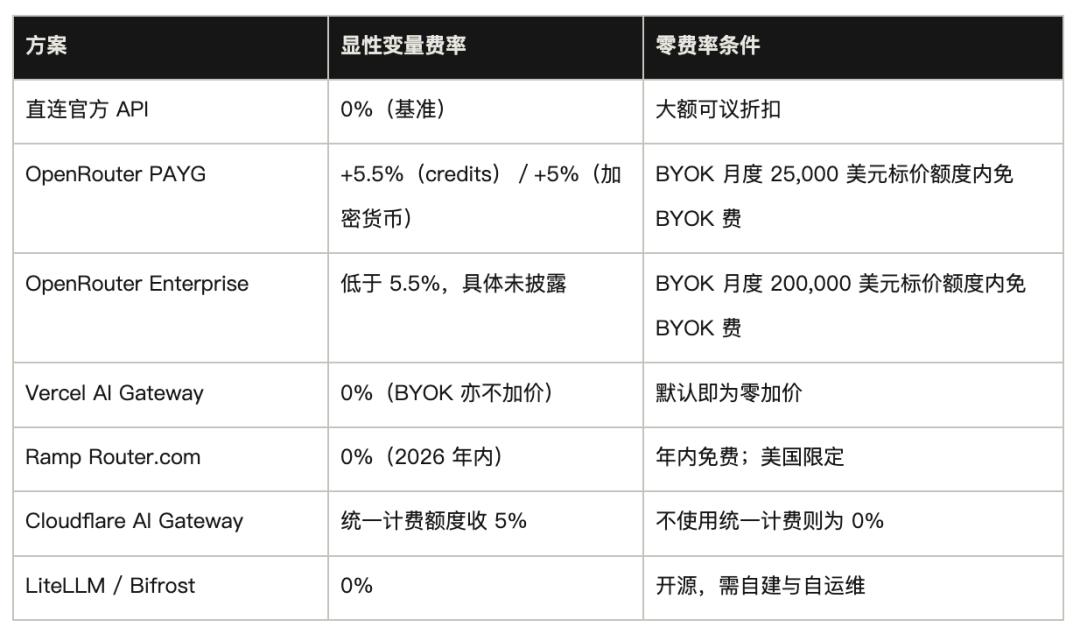
In a market flooded with relay-station platforms offering official prices at 30%, there are still customers paying a 5.5% premium. A highly credible explanation is counterparty trust: what is received is indeed this model, this context length, this inference configuration, and this supplier, and it will not be silently downgraded or swapped for another model.Trust is a meaningful differentiator for gray-market and long-tail relays; for large enterprise procurement, it is basically table stakes.
05 / Moat Deconstruction: Order Flow, Compute Liquidity, and the Intelligence Flywheel
▍5.1 Demand-Side Order Flow: Significant Scale, but Lacking Switching Barriers
Even if the API and routing code could be fully copied, order flow and its byproducts still constitute OpenRouter's only non-commoditized asset. It locks in four core powers: bargaining position with suppliers, distribution rights for cold-starting new models, the ability to direct traffic, and control over the customer's full-route relationship (identity permissions, billing budgets, usage analytics, discovery, and downgrade strategies).
However, this asset lacks defensibility: OpenAI interface compatibility has extremely lowered switching costs, and with pressure from Vercel/Cloudflare (existing ecosystem distribution), cloud giants (enterprise procurement bundling), Ramp (free purchase bonuses), and LiteLLM (large customers building in-house), multi-homing has become the industry norm.
▍5.2 Supply-Side Inference Services: A Mature Asset-Light Trading Market but Not Exclusive
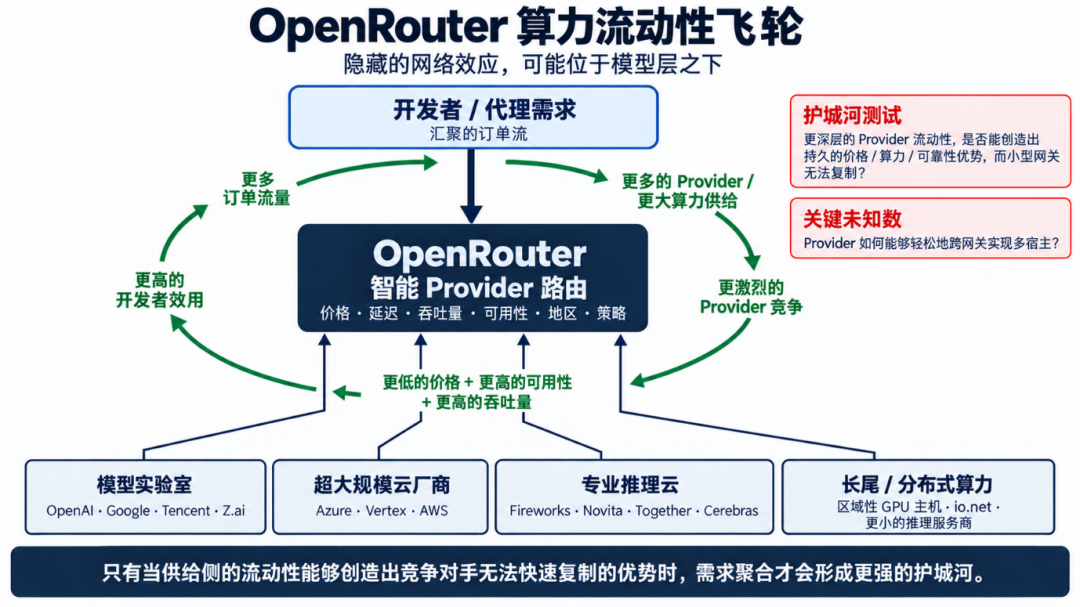
Figure 5 Computing the liquidity flywheel: the hidden network effects may lie beneath the model layer.
One of the more underappreciated layers of OpenRouter is the compute and provider liquidity beneath the models. The same model is often simultaneously hosted by multiple inference endpoints, and the platform continuously compares price, latency, throughput, availability, region, and data policies, then dynamically routes requests accordingly. For today's OpenRouter, this "provider intelligence" is actually more mature than model selection intelligence: it is already working in real production traffic.
The larger the order flow, the more it attracts access from more original model providers, cloud vendors, specialized inference clouds, and distributed compute; the more supply there is, the more fully price and performance compete, and the stronger the platform's appeal to the demand side. But this layer of the flywheel has a key limitation: providers can multi-home at low cost, simultaneously connecting to OpenRouter, Vercel, or other channels. Therefore, compute liquidity currently looks more like a leading asset that is difficult to accumulate, rather than a non-migratable exclusive moat.
▍5.3 Data assets: leading in scale, but the closed loop remains in an optional state
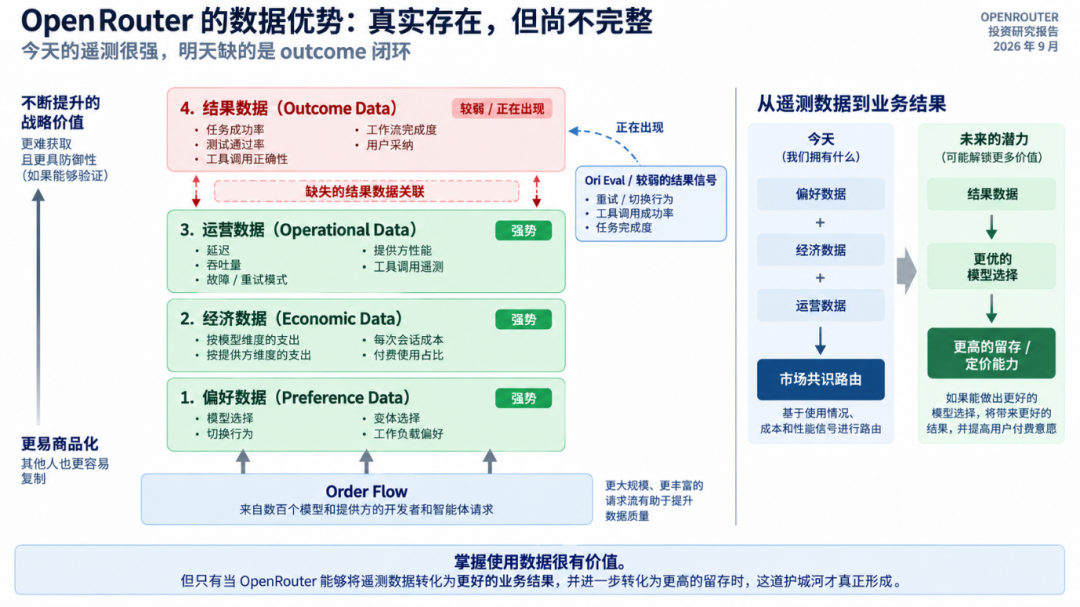
Figure 6 Four types of data and the missing outcome data loop.
OpenRouter has accumulated extremely strong and unique preference, economic, and operational performance data across models, providers, applications, and geographies—an exclusive perspective that original model labs (which see only their own traffic), self-hosted gateways (with no data aggregation), and cloud vendors (limited to their own cloud ecosystems) cannot match. Nevertheless, this data asset still faces two inherent technical and commercial limitations:
▪Endogeneity: The router's own choices change the traffic distribution, so the "performance data" is itself the result of algorithmic behavior.
▪Coverage bias: Private and some compliance-sensitive traffic does not enter public aggregation, and these customers are often the ones more willing to pay.
▪Sample bias: The model composition of Vercel and OpenRouter differs greatly, indicating that the data of any single gateway cannot directly represent the entire AI market.
At the level of the decision loop and adoption rate, the outcome-driven intelligence flywheel remains in an optionality state. On one hand, the loop has not been automated: the current Auto Router relies only on anonymized market spend signals from the past 7 days. Although behavioral metadata such as retries and interruptions is directly observable, the full loop of "production request → outcome scoring → automatic adjustment of routing weights" has not yet been closed. On the other hand, adoption has not been proven. Therefore, its model-selection intelligence should at this stage be rationally assessed as a forward option still in formation.
▍5.4 Dependency Chain: The Ceiling of the Data Moat Is Determined by Order Flow
Telemetry, Rankings, and Auto Router are all mechanically products of order flow.
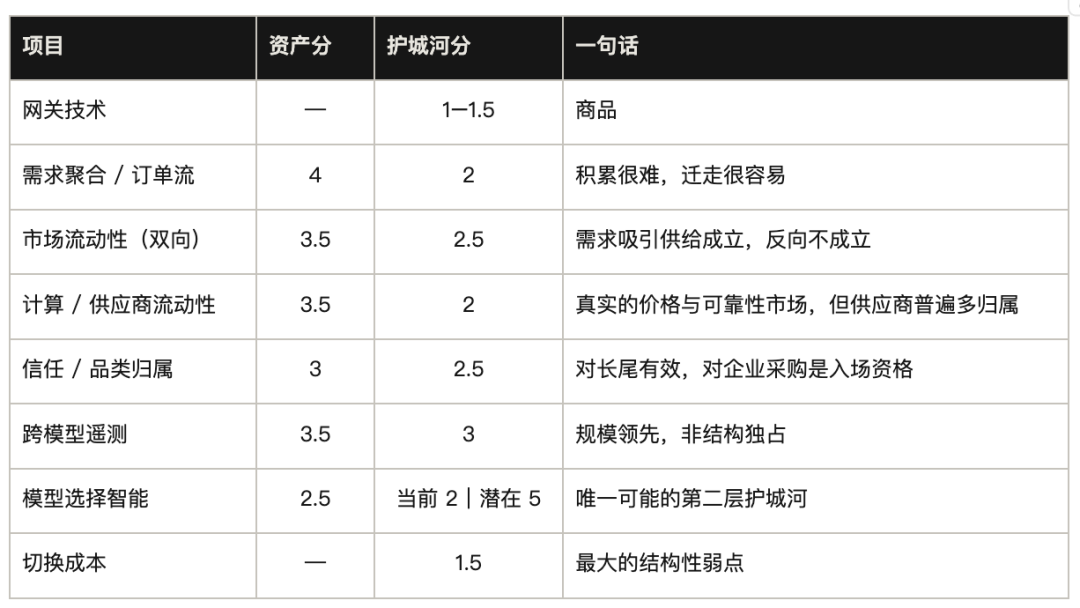
Competitors that capture order flow will eventually accumulate the same kind of data; and until routing intelligence is proven to improve outcomes, data itself does not generate retention independent of order flow. Therefore, the ceiling of the moat stack is determined by its weakest link, and that link is switching cost. This also redefines the direction of conversion strategy: routing algorithms are in principle rebuildable—as long as one obtains order flow of equivalent scale. What is truly non-portable is historical data that cannot be backfilled and the payment identity graph.
▍5.5 Moat Scorecard
Asset value and defensibility are scored separately. Low switching cost is the mechanism by which the asset fails to solidify and is not deducted again in other rows.
06 /Competition and Commoditization Pressure
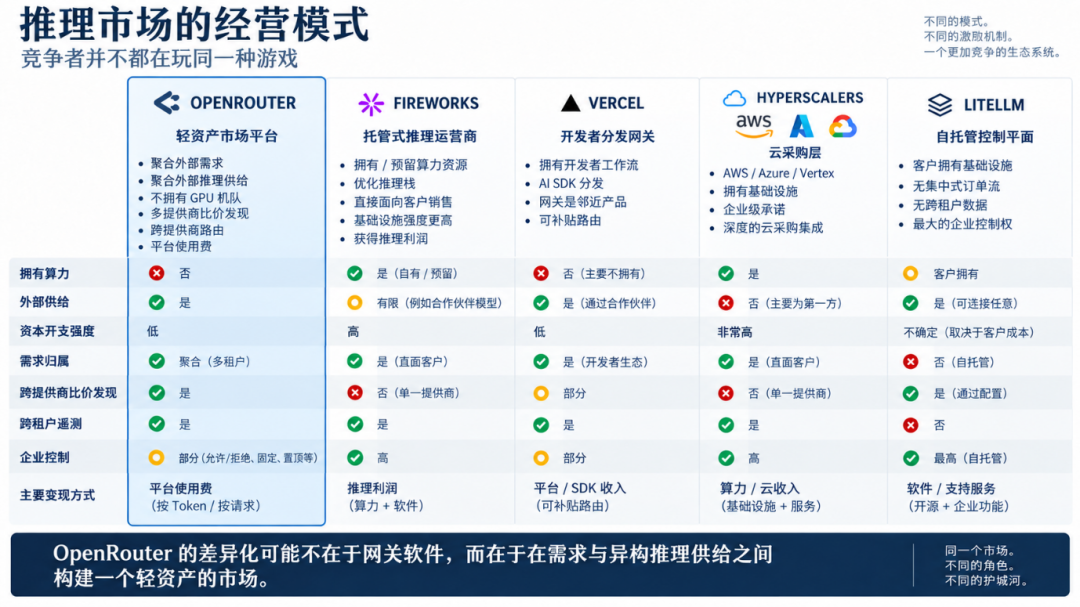
Figure 7 Five operating models in the inference market: competitors are not playing the same game.
Comparing competitors as if they were同类 gateways would be distorted. They differ structurally in compute self-ownership, external supply, capex intensity, demand attribution, cross-provider price discovery, cross-tenant telemetry, enterprise controls, and monetization methods—therefore their incentives differ, and their moats differ as well. OpenRouter's most distinctive structural feature is that it aggregates external demand and heterogeneous inference supply in an asset-light manner, and makes cross-provider routing itself the core product: it does not hold GPUs, aggregates external demand and external inference supply, and monetizes through platform fees.
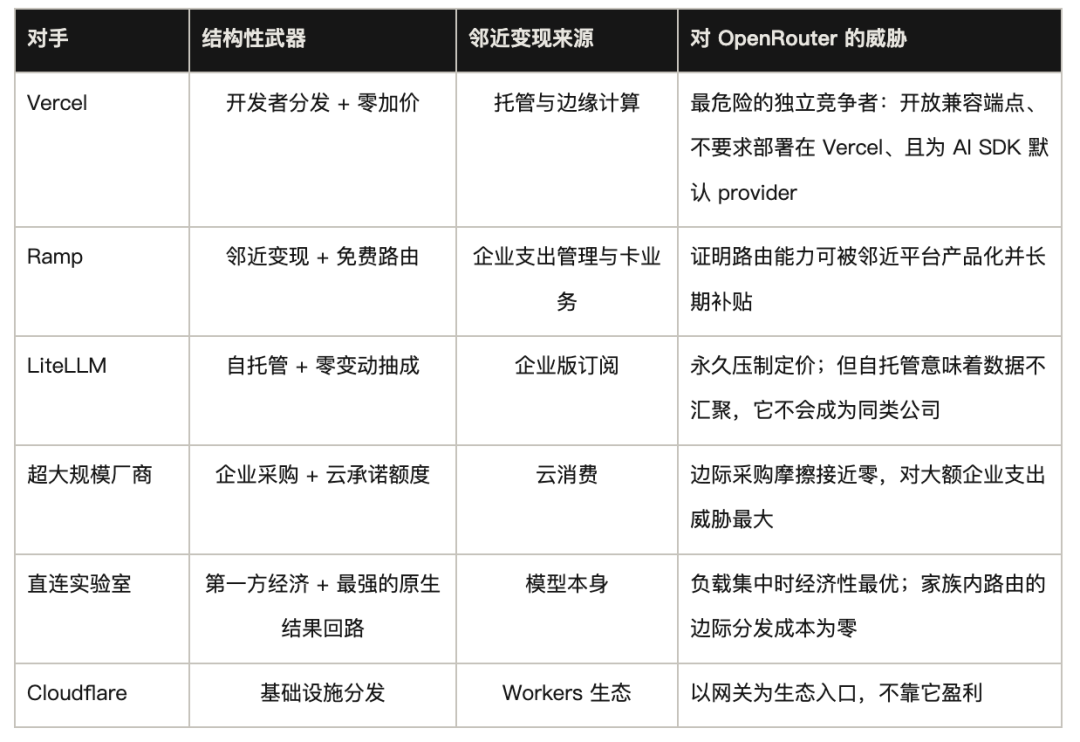
The most dangerous competitor is not another better gateway, but a company that doesn't need to make money from routing.
07 / Economics and Valuation
Has exponential usage growth translated into attractive financial economics?
Revenue = Paid GMV × Blended Take Rate; and Paid GMV = Paid Token Volume × Effective Price per Token.
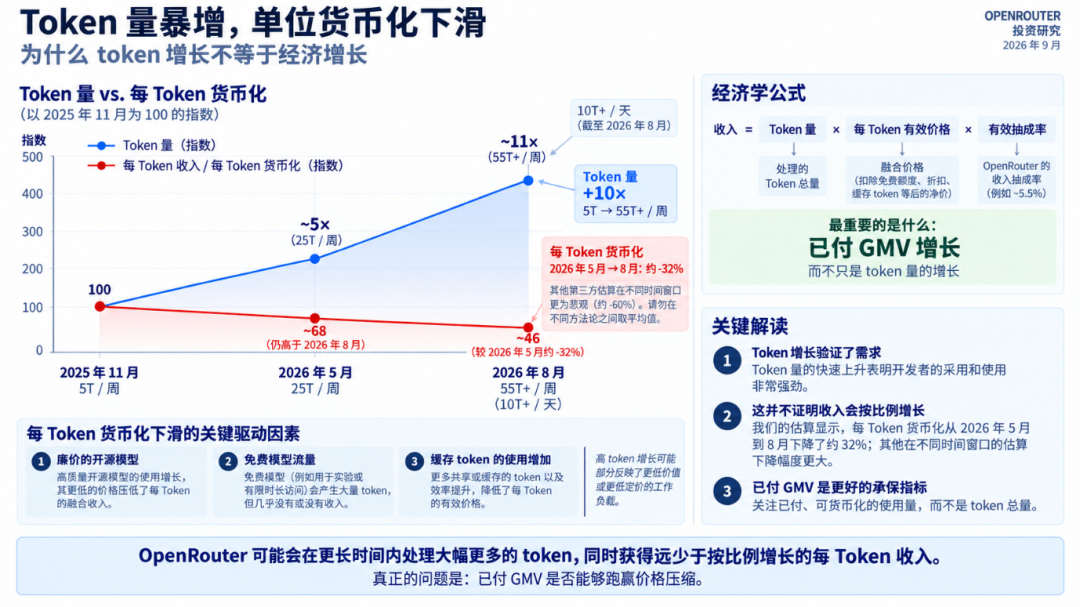
Figure 8 Volume is exploding, unit monetization is declining.
Among the three factors driving revenue growth, only Token processing volume is trending upward; both Token price and take rate face sustained downward pressure:
▪Volume explosion (the only upward factor): Weekly Token processing volume grew from 5 trillion in November 2025 to over 55 trillion in August 2026, a more than 10x increase in nine months.
▪Cliff-edge decline in unit monetization (the two downward factors): Revenue per trillion Tokens fell from $64.4k in May 2026 to $44.0k in August, a decline of approximately 32% over the period.
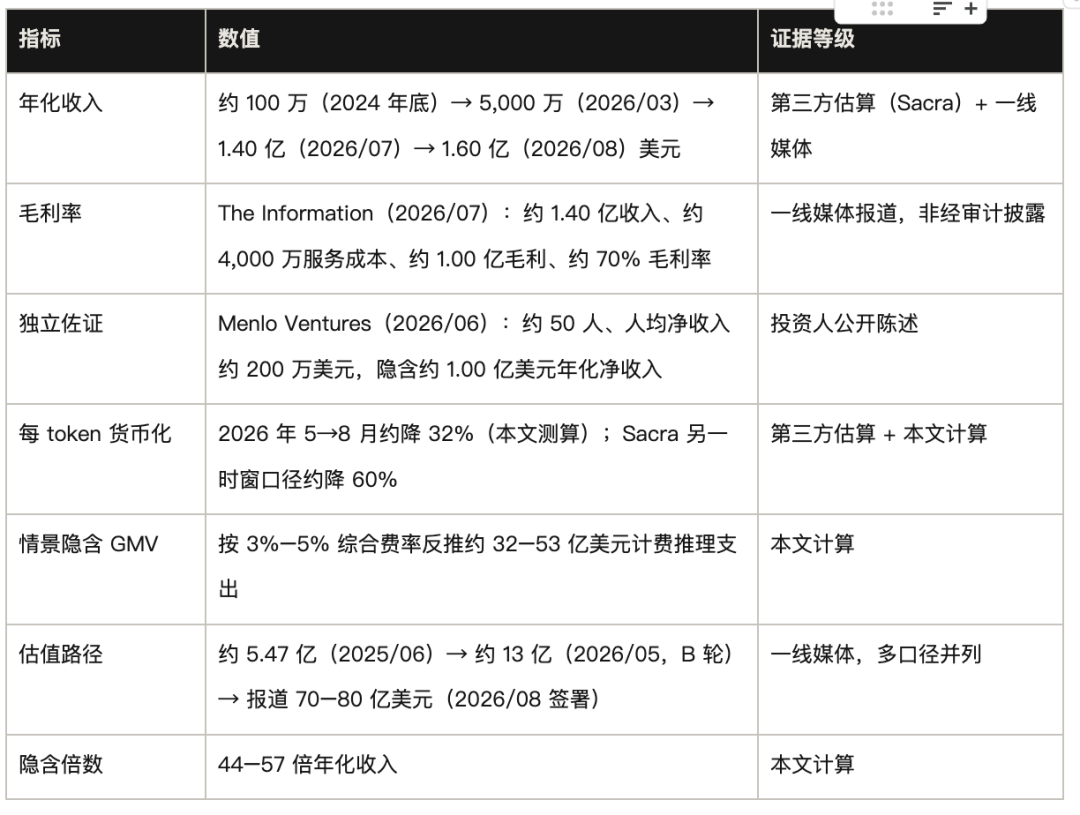
▍7.1 Financial Evidence
08 / Why Stripe Bought It
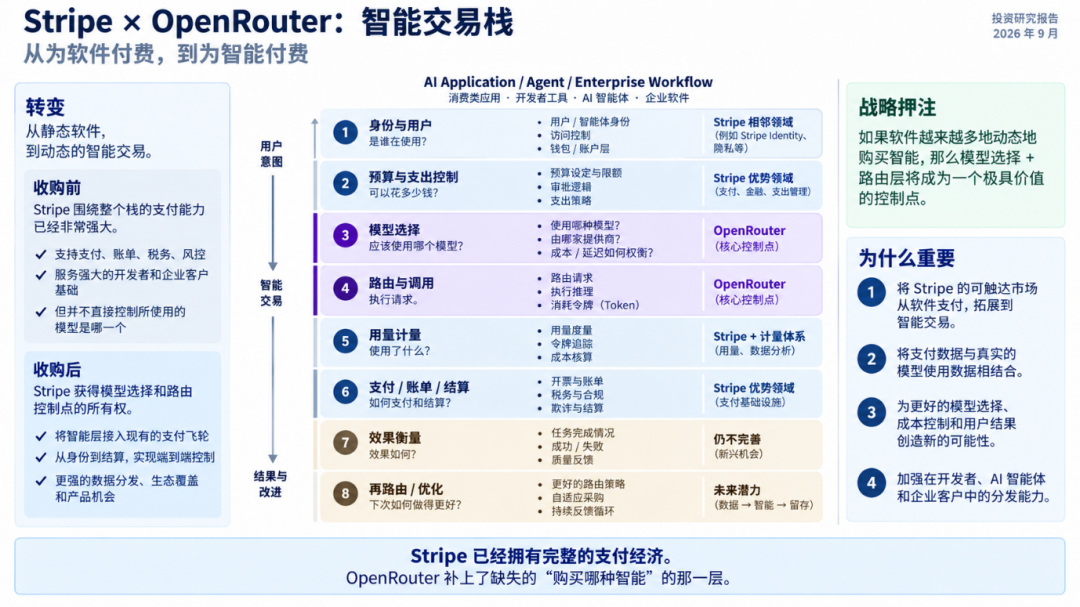
Figure 9 The eight layers of the intelligent transaction stack.
The framework in Stripe's August 19, 2026 investor letter is: capital and intelligence are becoming the two digital flows supporting every business; previously every developer needed to manage their revenue pipeline, which gave rise to Stripe; going forward every developer will likewise need to manage their intelligence pipeline.
▍8.1 Near-Term Economics: Not "Internalized Payments"
The two parties had already been deeply collaborating since January 2026: OpenRouter uses Stripe's Invoicing, Tax, and Radar, and already has token billing integration. The real incremental value of the acquisition lies in the deeper integration of ownership, product, and data, as well as more complete control over the chain of "who purchases which kind of intelligence, and how it is metered and settled."
▍8.2 Strategic Control Point
OpenRouter's value to Stripe is not in the "gateway" itself, but in its potential to become the orchestration layer for intelligent procurement: Stripe already controls identity, budgets, metering, payments, and settlement, while OpenRouter adds model selection and execution. Only by combining the two can there be an opportunity to cover the complete transaction chain of an Agent from budgeting to purchasing intelligence to settlement.
▍8.3 Long-Term Option
The long-term imagination space also comes precisely from here: Agent identity → budget → select models and vendors → consume intelligence → metering → settlement → measure results → re-optimize. Today, the last two steps are still missing. If OpenRouter cannot truly feed results back into future routing decisions, then it remains merely a smarter intermediary layer; if the closed loop is established, it could gradually become a control point for which Stripe would be willing to pay a high premium.
Conversely, this is also the biggest risk of the deal: if the most important control points in the Agent economy ultimately turn out to be budgeting and settlement, while model selection is merely a feature that can be provided for free, then OpenRouter's strategic value to Stripe will be lower than today's imagination suggests.
09 / Summary of Core Analytical Logic
Bull Case focuses on the demand explosion and a potential second-layer moat:
▪ Demand and liquidity have been fully validated: weekly token processing volume grew from 5 trillion to over 55 trillion, with approximately 9% compound weekly growth year-to-date;
▪ Agentic multi-model migration brings a structural tailwind, with token consumption 5–30 times that of standard chat and a substantial increase in the economic value of routing decisions;
▪ On the supply side, OpenRouter has become the go-to global cold-start platform for labs lacking their own distribution channels;
▪ Its accumulated cross-model telemetry data is mechanically impossible for other players to replicate;
▪ Meanwhile, outcome-aware routing constitutes a potential second-layer moat and comes with the corresponding tooling;
▪ Financially, its gross margin is approximately 70%, and combined with strong counterparty trust, this continues to underpin long-tail customers' willingness to pay.
Bear Case points directly at commoditization squeeze and the fragility of the business model:
▪ Routing functionality is rapidly becoming free infrastructure (Vercel at zero markup, Ramp free within the year, LiteLLM self-hosted at zero take rate);
▪ Customer switching costs are extremely low, technical migration takes hours, and multi-homing has become the default state;
▪ As large customers concentrate workloads and procurement scale rises, the incentive for Graduate Out—bypassing proportional take rates—increases significantly;
▪ Per-token monetization capacity continues to be diluted and is mechanically correlated with token growth;
▪ More critically, the outcome loop has yet to be proven, with both Auto Router adoption rates and causal lift lacking public evidence;
10 / Conclusion: OpenRouter Aggregates Value, But Does Not Lock It In for the Long Term
What OpenRouter demonstrates today is leadership, not a moat: it has successfully proven the value of demand aggregation and compute liquidity, yet has not proven customer lock-in; it has accumulated exclusive cross-model telemetry, yet lacks the most critical Outcome Data. Its strongest asset and its greatest weakness share the same origin—order flow can easily be diverted, suppliers universally multi-home, and platforms like Vercel and Ramp can at any time deliver a dimensional strike by making routing a free feature.
Stripe's $7.5 billion premium acquisition was by no means merely for an API traffic gateway, but rather a forward option: a bet on whether OpenRouter can leap from "traffic aggregation" to "intelligence generation," ultimately ascending to become the most core control point for model selection, metering, and settlement in the Agent economy.
In AI infrastructure investing, what is truly scarce is the decision-making advantage that, once traffic is accumulated, cannot be replicated by competitors through code alone. When competitors offer routing functionality as a free tool, can OpenRouter make customers unwilling to change that one line of base URL even when competitors' routing quotes are zero? The answer to this question determines whether $7.5 billion is a premium or a bargain.
Join the official Coincamps community:
Telegram: https://t.me/coin_camps
Recommended
Behind AVAX's Surge: 'Wall Street On-Chain' Becomes the New Main Theme
Sep 23, 12:12
Vitalik's Speech at Wanxiang Blockchain Week: Blockchain is Ending the Era of 'Everyone Repeating Everything'
Sep 23, 11:36
Pendle's 'Yield Black Hole' Ambition: Betting on Stablecoins, RWA, and Perpetual Contracts
Sep 23, 10:39
Frontier Models Ignite Price War | Rewire Morning News Brief
Sep 23, 10:33
Helping You Solve Your Troubles, Muse Might Be the AI That Ordinary People Need
Sep 22, 17:51
Quant Trader Takes on $40 Billion Kalshi Empire, Tearing Off the Fig Leaf of Trading Volume Fraud
Sep 22, 17:12